Insurance Agent Commission Rates in Kenya: What You Can Earn
"You can make KES 500,000 a month as an insurance agent!"
Heard that before?
Here's what they don't tell you:
That's not your first month. Probably not your first year either.
And it depends heavily on what you're selling.
Let me show you the real commission rates in Kenya. The legal maximums, straight from the regulator's rulebook.
Table of Contents
- How Insurance Commissions Actually Work
- Health Insurance Commission Rates
- Motor Insurance Commission Rates
- Life Insurance Commission Rates
- Other Insurance Products
- Tied Agent vs. Broker: Commission Differences
- How Much Can You ACTUALLY Earn?
- Commission Payment Terms
- What Affects Your Commission Rate?
- Negotiating Better Commissions
- Hidden Income Streams for Agents
- The Truth About "Passive Income"
- Upfront vs Renewal: Which Pays More?
- Track Every Commission
- Which Product Makes the Most Money?
- Commission Rate Red Flags
- Bottom Line
How Insurance Commissions Actually Work
Quick primer:
You sell a policy worth KES 50,000. Insurer pays you a percentage. That percentage is your commission rate.
Here's the part most guides skip: in Kenya that percentage has a legal ceiling.
The Insurance Regulations (Eleventh Schedule, regulation 22) set the maximum commission an insurer may pay an agent or a broker, class by class. An insurer can pay you less. It cannot legally pay you more.
So every number below is a cap, not a promise. Your actual rate is in your agency agreement.
Two types of commissions:
- First-year commission (when client first buys)
- Renewal commission (when client renews yearly)
For general insurance (health, motor, property), the cap is a flat percentage of each premium, first year and renewals alike. For life insurance, the cap is higher in year one and drops after.
Most agents focus on first-year commissions. Smart agents build renewal income.
Health Insurance Commission Rates
The bread and butter for most agents.
Legal maximum: 10% of the premium. That's "Medical Insurance" in the schedule.
Individual Health Plans
Same 10% cap, whichever insurer you sell for. Jubilee, AAR, Britam, CIC, APA: none of them may go above it.
Example:
- Client buys a KES 60,000 health policy
- Commission at the cap: 10% = KES 6,000 first year
- Renewal at the cap: 10% = KES 6,000 every year they renew
Group/Corporate Health Plans
Same 10% cap. The premiums are just much bigger.
Example:
- Company with 30 employees
- Premium: KES 2,000,000/year
- Commission at the cap: 10% = KES 200,000 a year
One corporate scheme can pay more than thirty individual policies. That's why agents chase them.
Motor Insurance Commission Rates
Second most popular product.
Legal maximum: 10% of the premium, for both private and commercial vehicles.
Comprehensive Motor Cover
Example:
- Car worth KES 2,000,000
- Premium: KES 80,000
- Commission at the cap: 10% = KES 8,000
Third-Party Motor Cover
Same 10% cap. Lower premiums, so smaller cheques.
Life Insurance Commission Rates
The biggest first-year commissions. Also the hardest to sell.
Term Life Insurance
| Policy type | Legal maximum |
|---|---|
| Term life (individual) | 10% of premium, for up to 10 years |
| Other individual life (endowment, education, whole life) | 50% of year 1, 20% of year 2, 5% of years 3-10 |
| Single-premium policies | 2% of the premium |
Example (term life):
- Annual premium: KES 50,000
- Commission at the cap: 10% = KES 5,000 a year
Example (education policy):
- Annual premium: KES 50,000
- Year 1 at the cap: KES 25,000
- Year 2: KES 10,000
- Years 3-10: KES 2,500 a year
That front-loading is why life agents push so hard for the first sale.
The catch: life policies usually take far longer to close than health.
Other Insurance Products
Legal maximums for the other classes you're likely to sell:
Property/Home Insurance
- Fire, domestic: 20%
- Fire, industrial: 25%
- Theft: 10%
Professional Indemnity
- Liability classes: 20%
Travel Insurance
Travel isn't a class of its own in the schedule. Ask the insurer which class it files the product under, and that cap applies.
WIBA (Work Injury Benefits)
- Workmen's compensation: 20%
Also worth knowing: personal accident 20%, engineering 20%, marine cargo 17.5%.
Tied Agent vs. Broker: Commission Differences
The caps are the same for agents and brokers. The schedule names both.
Tied agents (work for one company):
- Commission up to the cap, set by your agency agreement
- Some get allowances or targets-based support
- Less flexibility
Brokers (independent):
- Same caps, across many insurers
- No salary
- Full flexibility
Multi-tied agents:
- Same caps, a few insurers
- Some support from companies
- More options for clients
The difference isn't the percentage. It's how many products you can offer.
How Much Can You ACTUALLY Earn?
Let's do realistic math, at the legal cap. Your agreement may pay less.
Beginner Agent (Months 1-6)
Sales:
- 3 health policies/month @ KES 40,000 avg
- 1 motor policy/month @ KES 60,000
Commissions:
- Health: 3 × KES 40,000 × 10% = KES 12,000
- Motor: 1 × KES 60,000 × 10% = KES 6,000
Total: KES 18,000/month
Mid-Level Agent (Year 1-2)
Sales:
- 8 health policies/month @ KES 40,000
- 3 motor policies/month @ KES 60,000
- Growing renewal base
Commissions:
- Health: 8 × KES 40,000 × 10% = KES 32,000
- Motor: 3 × KES 60,000 × 10% = KES 18,000
Total: KES 50,000/month in new business, plus renewals on top
Top Performer (Year 3+)
Sales:
- 15 health policies/month @ KES 40,000
- 5 motor policies/month @ KES 60,000
- 1-2 corporate deals/year
- Strong renewal income
Commissions:
- Health: 15 × KES 40,000 × 10% = KES 60,000
- Motor: 5 × KES 60,000 × 10% = KES 30,000
- One KES 2M corporate scheme: KES 200,000 a year
Total: KES 90,000/month in new individual business, plus corporate and renewals
Commission Payment Terms
Here's what they don't tell you upfront.
When Do You Actually Get Paid?
Most insurers pay commissions after the client pays the premium.
Typical order:
- Client pays premium
- Insurer processes payment
- Commission paid to you, usually weeks later
Your agency agreement says exactly when.
Pro tip: Track every policy. Follow up on late payments.
Chargebacks (The Hidden Risk)
If a client cancels early, you might have to return the commission.
Check the clawback clause in your agreement before you sign.
How to avoid:
- Sell to serious buyers only
- Follow up on renewals
- Keep clients happy
What Affects Your Commission Rate?
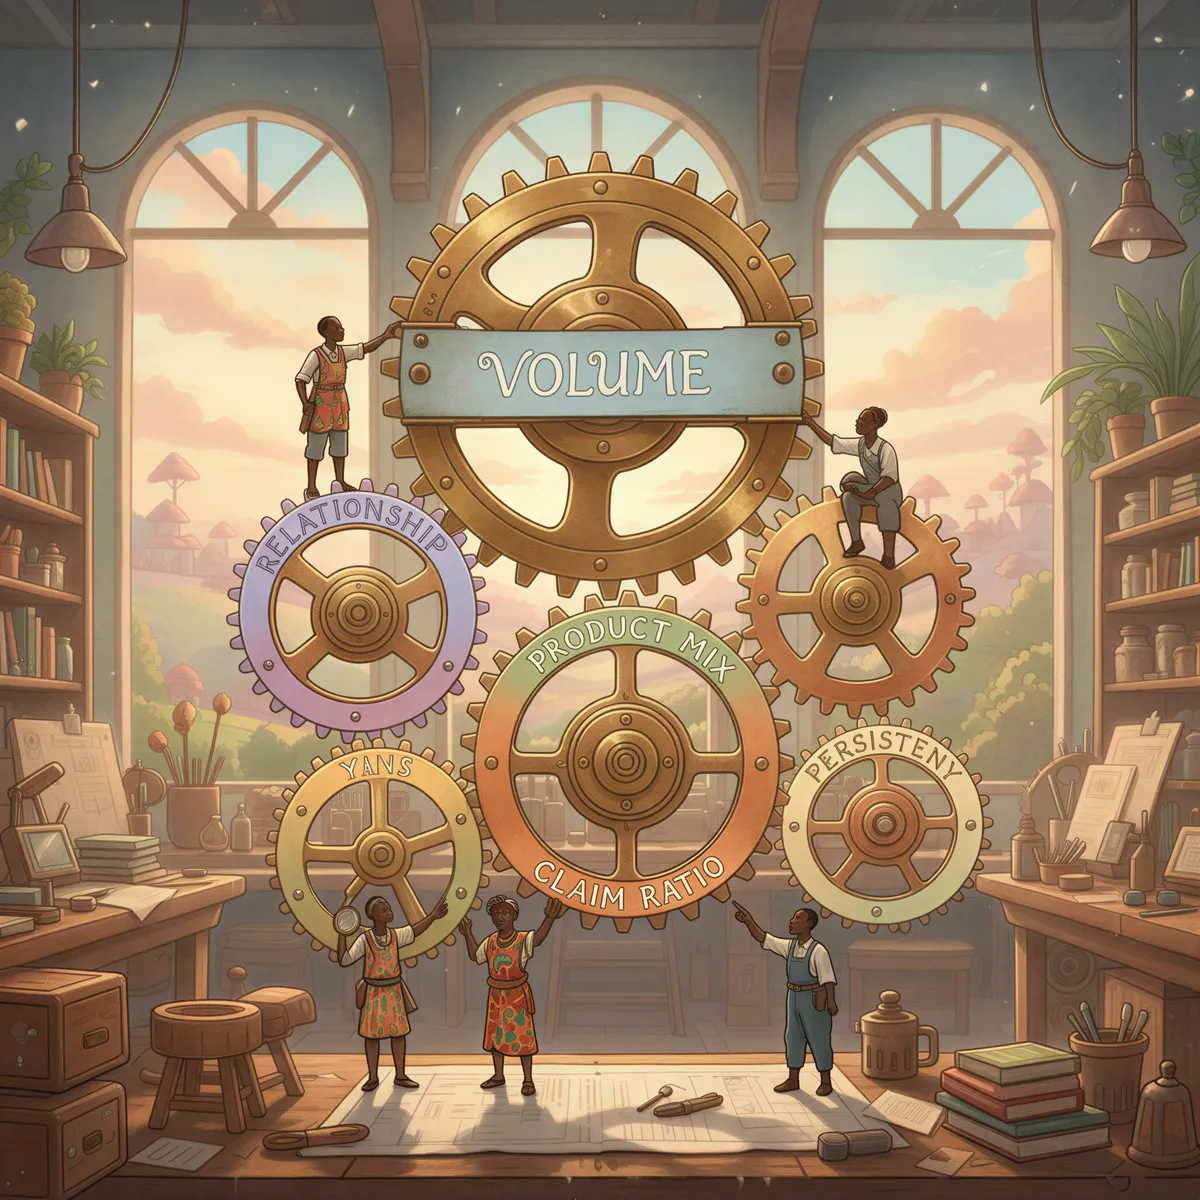
1. Your Volume Bigger producers negotiate better terms, up to the legal cap and never above it.
2. Your Relationship with the Insurer Long-term agents get better treatment.
3. Product Mix Life pays more up front. Health and motor pay steadily.
4. Claim Ratio If your clients file too many claims, insurers get less keen on your business.
5. Persistency Clients who renew keep paying you.
Negotiating Better Commissions
Yes, you can negotiate. Just not past the cap.
When you have leverage:
- You bring in corporate clients
- You've built a real book of annual premiums
- You're switching from another insurer
What to ask for:
- A rate closer to the cap
- Faster payment terms
- Marketing support
- Training and leads
Don't ask for:
- Rates above the legal maximum
- Better rates with zero sales history
- Commissions on non-existent deals
Hidden Income Streams for Agents
Commissions aren't the only way to earn.
1. Renewals Every renewal pays you again on general insurance.
2. Corporate Schemes One group medical scheme can out-earn a month of retail sales.
3. Cross-Selling Sell health + motor to the same client. Two commissions, one relationship.
4. Referrals Happy clients send you their colleagues.
5. Life Policies Over Time Years 2-10 of a life policy keep paying, just at lower rates.
The Truth About "Passive Income"
Agents love to brag about renewal commissions.
"I make KES 100k/month in renewals alone!"
Reality check:
Renewals are only "passive" if clients actually renew. Not all of them do.
And do the math at the cap. KES 100k a month is KES 1.2M a year. At 10%, that's about KES 12M of premium renewing every year.
It's possible. But it's not quick.
Upfront vs Renewal: Which Pays More?
Two agents. Same effort on new business. Different habits after the sale.
Both sell 20 health policies a year at an average KES 60,000 premium. Both earn the 10% cap on new business and on renewals.
- Agent A moves on after the sale. 60% of clients renew.
- Agent B checks in, chases renewals, helps with claims. 90% renew.
| Year | Agent A renewals | Agent A income | Agent B renewals | Agent B income |
|---|---|---|---|---|
| 1 | 0 | KES 120,000 | 0 | KES 120,000 |
| 2 | 12 | KES 192,000 | 18 | KES 228,000 |
| 3 | 19 | KES 234,000 | 34 | KES 324,000 |
| 4 | 24 | KES 264,000 | 49 | KES 414,000 |
| 5 | 26 | KES 276,000 | 62 | KES 492,000 |
Five-year total: about KES 1.09 million for A. About KES 1.58 million for B.
Same new sales. B earns roughly KES 490,000 more, and the gap widens every year after that.
When Upfront Still Wins
- You need cash flow now. Bills don't wait for year three.
- The product lapses anyway. Short credit-life covers, entry plans people outgrow.
- You're running pure volume. It works. It's also how agents burn out.
The Balance That Works
- Years 1-2: lean on new business. You need the cash.
- Years 3-5: build the retention habit. Renewal reminders, an annual review call, claims help.
- After that: your renewals carry you while you keep selling.
Retained clients also refer. That's new business you didn't pay for.
Track Every Commission
Insurers make mistakes. Under-payments happen. You only catch them if you track.
One spreadsheet, one row per policy:
- Client name
- Policy number
- Product
- Premium
- Commission rate
- Expected commission
- Actual received
- Renewal date
Review it monthly. Query any gap within 30 days, while the paperwork is fresh.
Which Product Makes the Most Money?
Short answer: it depends on your timeline.
- Health: up to 10% every year it renews, and everyone needs it
- Motor: up to 10%, quick to sell, renews yearly
- Life: up to 50% in year one on most policies, then far less, and slow to close
Health is where most agents start. Life is where the big first-year cheques are.
Commission Rate Red Flags
Walk away if someone offers:
-
Commission above the legal caps → On general insurance, nothing above 25% is allowed for any class. On health and motor, nothing above 10%.
-
Upfront commissions before client pays → You'll owe money back if the client doesn't pay
-
"Join and earn 40% on everything" → That's not an insurer. That's a recruitment scheme.
-
No written commission agreement → You'll fight for every payment
Legitimate insurers pay within the caps, with clear written terms.
Bottom Line
Health insurance: up to 10% of every premium, first year and renewals Motor insurance: up to 10% of every premium Life insurance: up to 50% of year one on most policies, 10% a year on term life
Start with health. Build your renewal base. Add motor for quick wins. Try life when you're experienced.
And remember: Commission rates don't matter if you're not selling.
Focus on getting clients first. Negotiate better terms later.
Start Generating Quotes in Minutes
Compare quotes from Kenya's leading insurers and send a client a proposal in under a minute.
No credit card required.
Get quotes from 40+ underwriters in under 30 seconds.
All quotes meet Insurance Regulatory Authority standards.
Never miss a commission payment with automatic tracking.