Family Health Insurance Kenya: From KES 45,000 a Year
Last month, my cousin paid KES 180,000 for his daughter's appendectomy.
Out of pocket.
No insurance.
The surgery went fine. But his savings account? Not so much.
Here's what nobody tells you about family health insurance:
It's not about IF you'll need it. It's about WHEN.
And when that day comes, you don't want to be choosing between quality care and your retirement fund.
Table of Contents
- What Is Family Health Insurance?
- Who Gets Covered?
- What Does It Actually Cover?
- How Much Does Family Health Insurance Cost in Kenya?
- The 3 Types of Family Plans
- What You DON'T Need (But Agents Will Try to Sell You)
- How to Choose the Right Family Plan
- Best Family Health Insurers in Kenya
- The Hidden Costs Nobody Warns You About
- Common Mistakes Families Make
- How to Save Money on Family Health Insurance
- What to Do When You Need to Use Your Insurance
- When to Add Extended Family (Parents)
- Should You Get SHA + Private Insurance?
- How to Compare Family Insurance Quotes (in 5 Minutes)
- Red Flags to Watch Out For
- Is Family Health Insurance Worth It?
- Next Steps
What Is Family Health Insurance?
Simple answer:
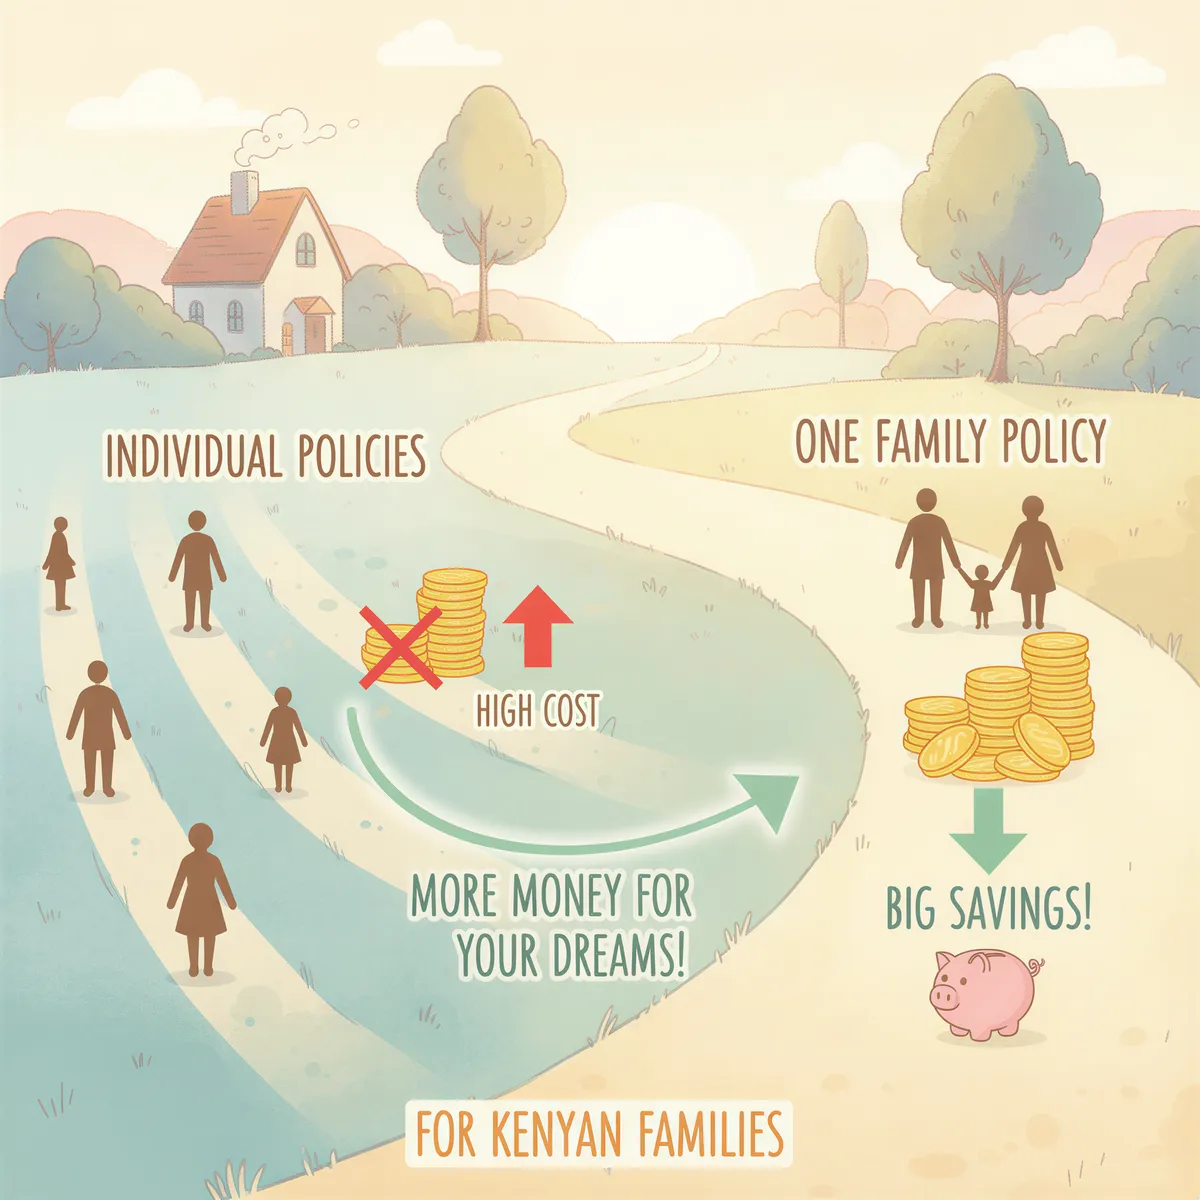
One policy that covers everyone in your household.
Instead of buying separate policies for:
- You
- Your spouse
- Your kids
- Maybe your parents
You get one plan. One premium. One renewal date.
Easier to manage. Usually cheaper.
Who Gets Covered?
Standard family health insurance in Kenya covers:
✔ Primary member (you) ✔ Spouse (legally married) ✔ Children (up to 4 kids, under 18-25 years)
Some insurers also cover: ✔ Parents (as dependents, at extra cost) ✔ Adopted children ✔ Adult children (if in university/college)
Pro tip: Kids are cheap to insure. Add them now while they're young and healthy.
What Does It Actually Cover?
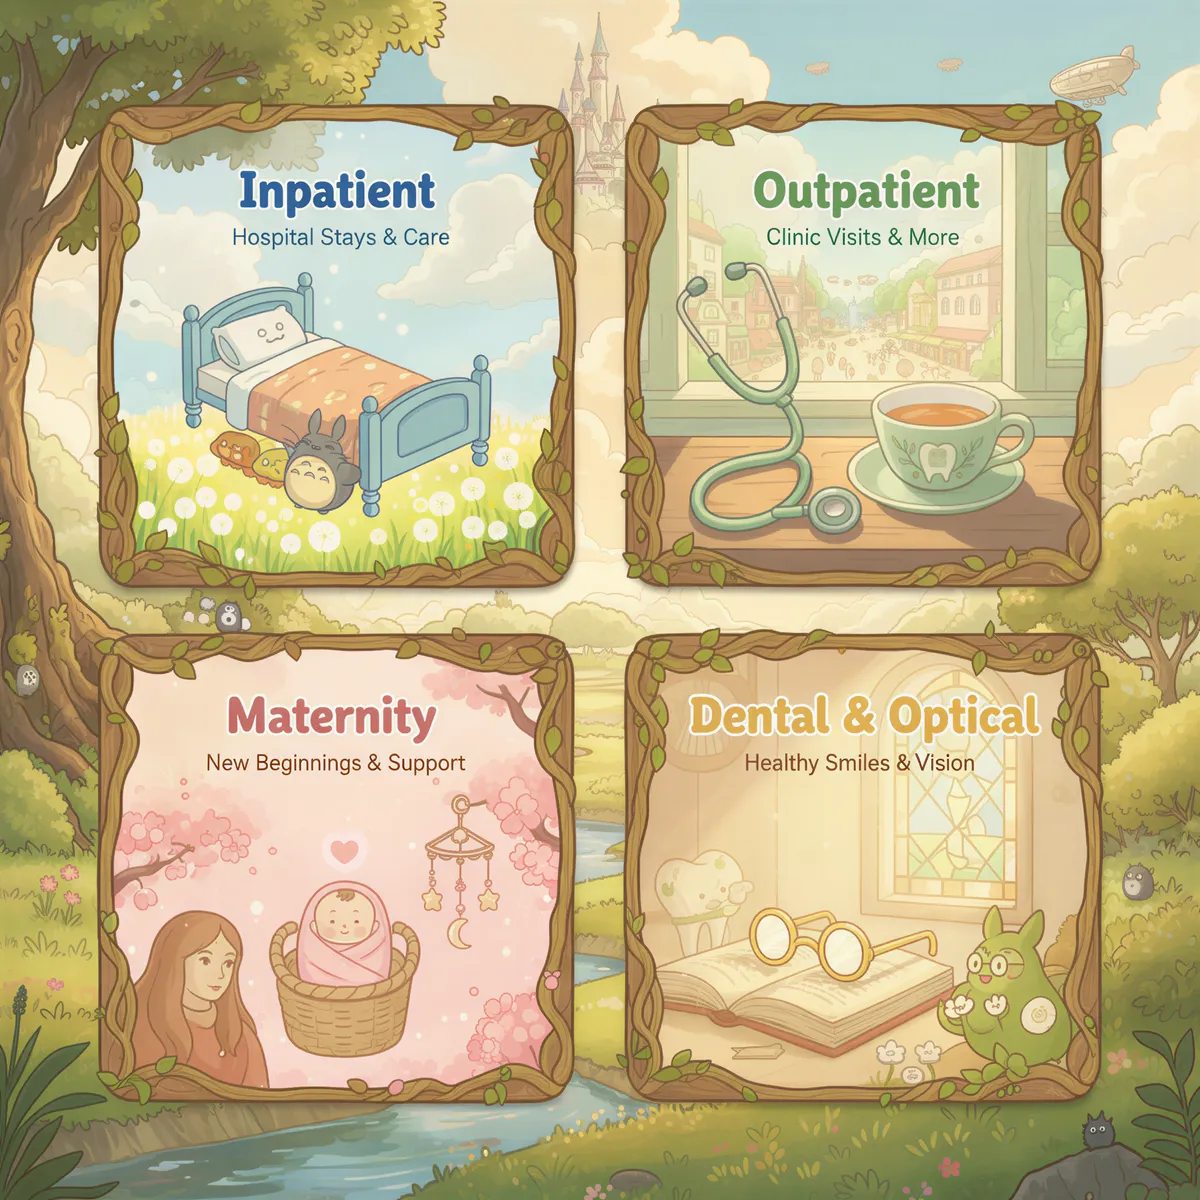
Most family health plans include:
Inpatient Cover
- Hospital admission
- Surgery
- ICU/HDU
- Medication during admission
- Doctor fees
Outpatient Cover (Optional)
- Regular doctor visits
- Lab tests
- X-rays/scans
- Prescriptions
- Specialist consultations
Maternity (Optional)
- Pre-natal checkups
- Delivery (normal or C-section)
- Post-natal care
- Newborn cover (first 90 days)
Dental & Optical (Optional)
- Dental checkups, fillings, extractions
- Eye tests, glasses, contact lenses
How Much Does Family Health Insurance Cost in Kenya?
Real numbers from 2026:
| Family Size | Inpatient Only | Inpatient + Outpatient | Full Package (Inc. Maternity) |
|---|---|---|---|
| Couple (2 adults) | KES 35,000 - 45,000 | KES 55,000 - 70,000 | KES 65,000 - 80,000 |
| Couple + 1 child | KES 40,000 - 50,000 | KES 60,000 - 75,000 | KES 70,000 - 90,000 |
| Couple + 2 children | KES 45,000 - 55,000 | KES 65,000 - 85,000 | KES 80,000 - 100,000 |
| Couple + 3-4 children | KES 50,000 - 65,000 | KES 75,000 - 95,000 | KES 90,000 - 115,000 |
These are annual premiums.
You can pay:
- Monthly (slightly more expensive)
- Quarterly
- Annually (usually 5-10% discount)
The 3 Types of Family Plans
Type 1: Principal + Dependents
How it works: You're the main member. Everyone else is a "dependent."
Pros:
- Cheaper
- Simple structure
Cons:
- If you leave your job (if employer-sponsored), family loses cover
Type 2: Dual Principal
How it works: Both you and your spouse are "principals." Kids are dependents.
Pros:
- Better coverage continuity
- Two separate annual limits
Cons:
- More expensive
Type 3: Blended Family Plans
How it works: Custom plans for blended families, single parents, or multi-generational households.
Pros:
- Flexible
Cons:
- Not all insurers offer this
Most families go with Type 1. It's the standard.
What You DON'T Need (But Agents Will Try to Sell You)
1. Last Expense Cover This is burial insurance. Different product. Don't bundle it unless you actually want it.
2. Critical Illness Riders These pay lump sums for cancer, stroke, etc. Useful, but expensive. Start with basic health cover first.
3. International Cover Unless you travel 3+ times/year, skip it. Medical tourism is rare.
4. Unlimited Everything "Unlimited" inpatient cover sounds nice. But it costs 40-60% more. And you'll probably never hit the limit anyway.
How to Choose the Right Family Plan
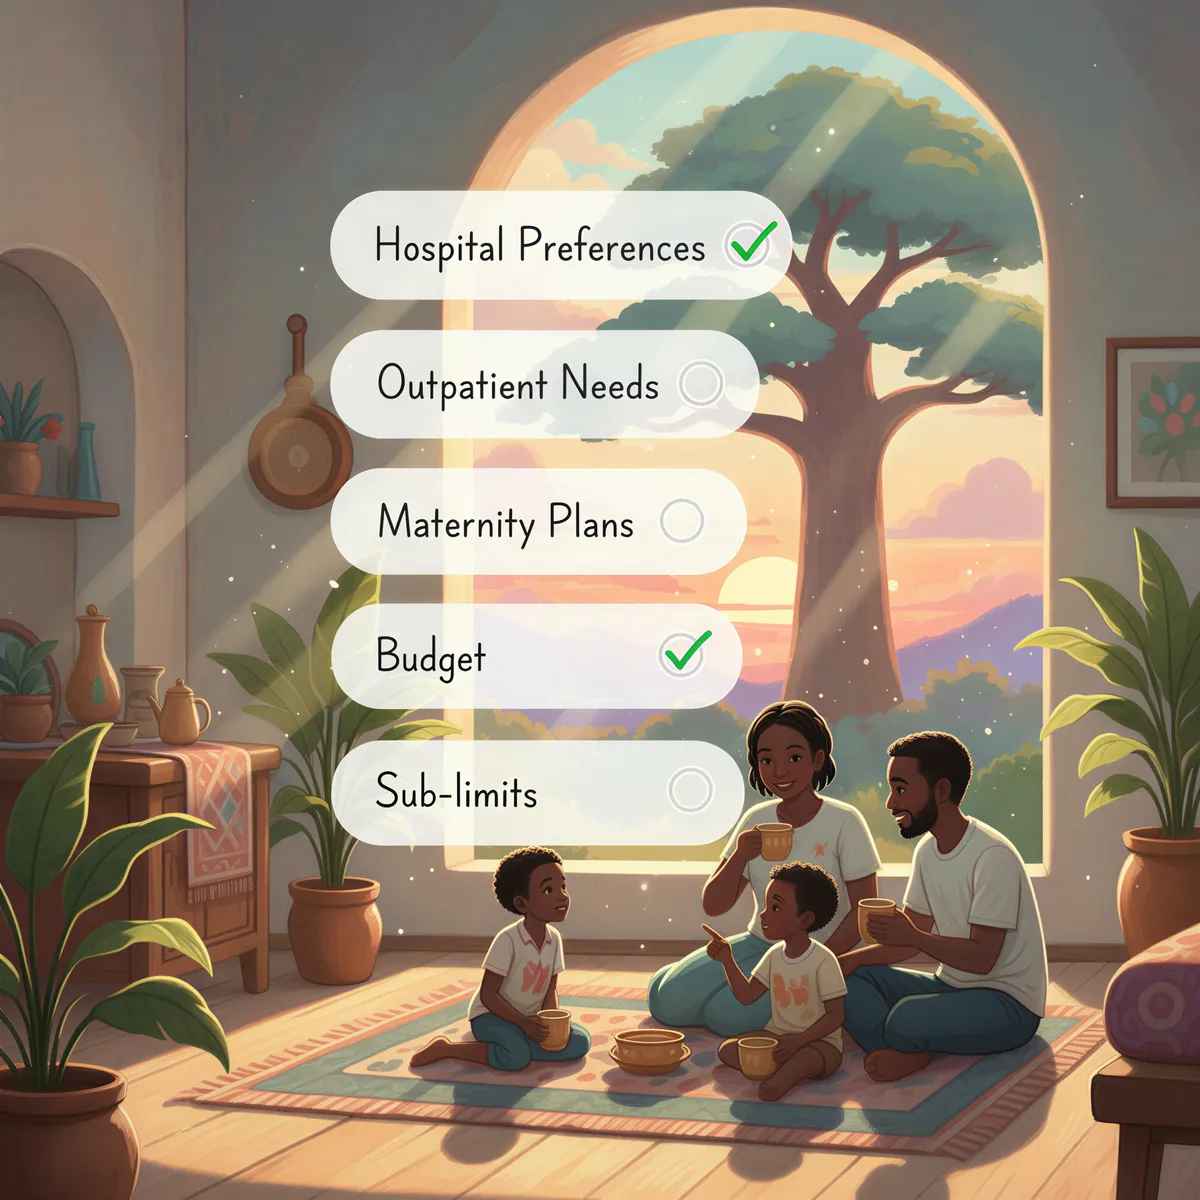
Ask yourself these 5 questions:
1. What hospitals do we prefer?
Check if your insurer covers them. No point having insurance if you can't use your preferred hospital.
2. Do we need outpatient?
If your kids get sick often (malaria, flu, etc.), outpatient is worth it. Otherwise, inpatient-only saves you 30-40%.
3. Are we planning more kids?
Then maternity cover is a must. Add it before pregnancy, or you'll wait 10-12 months.
4. What's our budget?
Be honest. Don't stretch yourself thin. A basic plan you can afford > a premium plan you'll cancel.
5. What are the sub-limits?
Every plan has limits on specific things:
- Surgery: KES 500,000 max
- ICU: KES 30,000/day
- Outpatient: KES 100,000/year
Read the fine print.
Best Family Health Insurers in Kenya
Based on hospital network, claims, and value:
Top Pick for Most Families:
- Jubilee Health Insurance — Best maternity cover, solid network, reliable
Best for Budget-Conscious Families:
- Britam Health — Affordable, growing network, good value
Best for Maximum Hospital Choice:
- AAR Insurance — Largest network, fast approvals, premium pricing
Best for Transparency:
- Resolution Health — Clear pricing, great customer portal, specialist focus
No insurer is perfect. Pick based on your priorities.
The Hidden Costs Nobody Warns You About
1. Age-Based Premium Hikes Your premium goes up as you (and your spouse) get older. Expect 10-15% annual increases.
2. Co-Payments Some plans make you pay 10-20% of every bill. Check before buying.
3. Pre-Existing Condition Waiting Periods If someone in your family has diabetes, hypertension, etc., expect 1-2 year waiting periods.
4. Renewal Rejections If you make too many claims, insurers can refuse to renew. Rare, but it happens.
5. Geographic Restrictions Some cheaper plans only work in Nairobi/major cities. If you live upcountry, verify coverage.
Common Mistakes Families Make
Mistake 1: Buying Individual Policies Instead of Family Plans You'll pay 30-50% more. Always ask for family rates.
Mistake 2: Adding Maternity AFTER Getting Pregnant Won't work. Maternity has 10-12 month waiting periods.
Mistake 3: Only Covering Inpatient Kids get sick. A lot. Outpatient cover pays for itself if you have young kids.
Mistake 4: Not Reading Exclusions Cosmetic surgery? Not covered. Sports injuries? Maybe not covered. Check.
Mistake 5: Letting Policies Lapse Miss one payment, lose your cover. Set up auto-renewals.
How to Save Money on Family Health Insurance
1. Pay Annually Saves 5-10% vs. monthly payments.
2. Skip Unnecessary Add-Ons Dental, optical, travel cover — only add if you'll actually use them.
3. Choose Higher Co-Payments Agree to pay 10-20% of bills yourself. Premium drops 15-25%.
4. Start Young Premiums are based on age. Lock in low rates early.
5. Compare Multiple Quotes Use a comparison tool. You'll find the same cover for 20-30% less.
What to Do When You Need to Use Your Insurance
Step 1: Check If Your Hospital Is Covered Call your insurer's hotline or check their app.
Step 2: Get Pre-Authorization (for planned treatments) For surgeries, maternity, etc., inform your insurer 48-72 hours ahead.
Step 3: Present Your Insurance Card At hospital reception. They'll verify directly with the insurer.
Step 4: Track Your Claim Most insurers have online portals. Monitor approval status.
Step 5: Pay Any Co-Payments or Excluded Items Like ambulance fees, private room upgrades, etc.
When to Add Extended Family (Parents)
Adding parents to your family plan costs extra.
It makes sense if:
- They're under 65 (premiums skyrocket after that)
- They're healthy (pre-existing conditions = high premiums)
- You're already buying a family plan (bundling saves money)
It doesn't make sense if:
- They're over 70 (better to get senior-specific plans)
- They have multiple chronic illnesses (individual plans might be better)
- Your employer covers them separately
Should You Get SHA + Private Insurance?
SHA (Social Health Authority) is mandatory. Everyone pays through payroll deductions.
But SHA only covers:
- Public hospitals
- Basic care
- Long queues
- Shared wards
Private insurance adds:
- Private hospitals
- Fast service
- Private rooms
- Specialist access
Bottom line: You need both. SHA as your base. Private insurance as your upgrade.
How to Compare Family Insurance Quotes (in 5 Minutes)
Don't call 10 different agents.
Use a comparison tool like BimaSasa.
You'll see:
- Side-by-side coverage
- Pricing from multiple insurers
- Hospital networks
- Real terms & conditions
Takes 5 minutes. Saves you KES 10,000 - 30,000/year.
Red Flags to Watch Out For
1. "This plan covers absolutely everything" No it doesn't. Every plan has exclusions.
2. "Pay now or lose this discount" Pressure tactics. Walk away.
3. "We'll handle your claims directly" Claims go through insurers, not agents. This is a lie.
4. "No medical exams needed" True for most plans. But pre-existing conditions still have waiting periods.
If an agent uses these lines, find another agent.
Is Family Health Insurance Worth It?
Let's do the math.
Scenario 1: No Insurance
- Appendectomy: KES 180,000
- Normal delivery: KES 120,000
- ICU (3 days): KES 150,000
Total potential cost: KES 450,000+
Scenario 2: Family Insurance
- Annual premium: KES 70,000
- Out-of-pocket (co-payments): KES 10,000
Total cost: KES 80,000
You save: KES 370,000
And that's just one incident.
Next Steps
- List your must-have hospitals
- Decide: inpatient-only or inpatient + outpatient?
- Set your budget
- Get 3+ quotes from different insurers
- Compare coverage, not just price
- Buy before someone gets sick
Don't wait for a medical emergency to think about insurance.
By then, it's too late.
Start Generating Quotes in Minutes
Compare quotes from Kenya's leading insurers and send a client a proposal in under a minute.
No credit card required.
Get quotes from 40+ underwriters in under 30 seconds.
All quotes meet Insurance Regulatory Authority standards.
Never miss a commission payment with automatic tracking.