NHIF Top-Up Plans Kenya 2026: Are They Worth It?
My neighbor pays KES 3,000/month to SHA.
"Why do I need private insurance?" he asked. "I'm already covered."
Then his daughter broke her arm.
Public hospital wait: 6 hours. Shared ward. Basic treatment.
He paid KES 12,000 out of pocket for private hospital instead.
That's why you need a top-up plan.
SHA covers basics. Top-ups cover comfort.
Table of Contents
- What Is a SHA Top-Up Plan?
- What SHA Actually Covers (The Basics)
- What Top-Up Plans Cover
- How Much Do Top-Up Plans Cost?
- Types of Top-Up Plans
- Best SHA Top-Up Insurance Providers
- How Top-Up Insurance Works (Real Example)
- Common Mistakes People Make
- Is a Top-Up Worth It?
- What Top-Ups DON'T Cover
- Can You Have Multiple Top-Ups?
- How to Buy a SHA Top-Up Plan
- Do You Need Outpatient Top-Up?
- SHA vs Private Insurance vs Top-Up: Final Comparison
- What If Your Employer Provides Group Insurance?
- Can You Cancel Your Top-Up?
- Top-Up for Seniors (60+ Years)
- Next Steps
What Is a SHA Top-Up Plan?
Simple explanation:
SHA (Social Health Authority) = Basic government health cover
Top-up plan = Private insurance that fills the gaps
Together = Complete health coverage
Think of SHA as economy class. Top-up as business class upgrade.
What SHA Actually Covers (The Basics)
SHA replaced NHIF in 2024.
What you get:
✔ Public hospital care ✔ Inpatient services (government facilities) ✔ Outpatient services (at government clinics) ✔ Essential medications ✔ Basic surgeries ✔ Maternity care (public hospitals)
What you don't get:
✘ Private hospitals ✘ Fast service ✘ Private rooms ✘ Advanced treatments ✘ Specialist access without long waits ✘ Comprehensive medication
Reality: SHA covers emergencies. But comfort? Speed? Choice? You'll pay extra.
What Top-Up Plans Cover
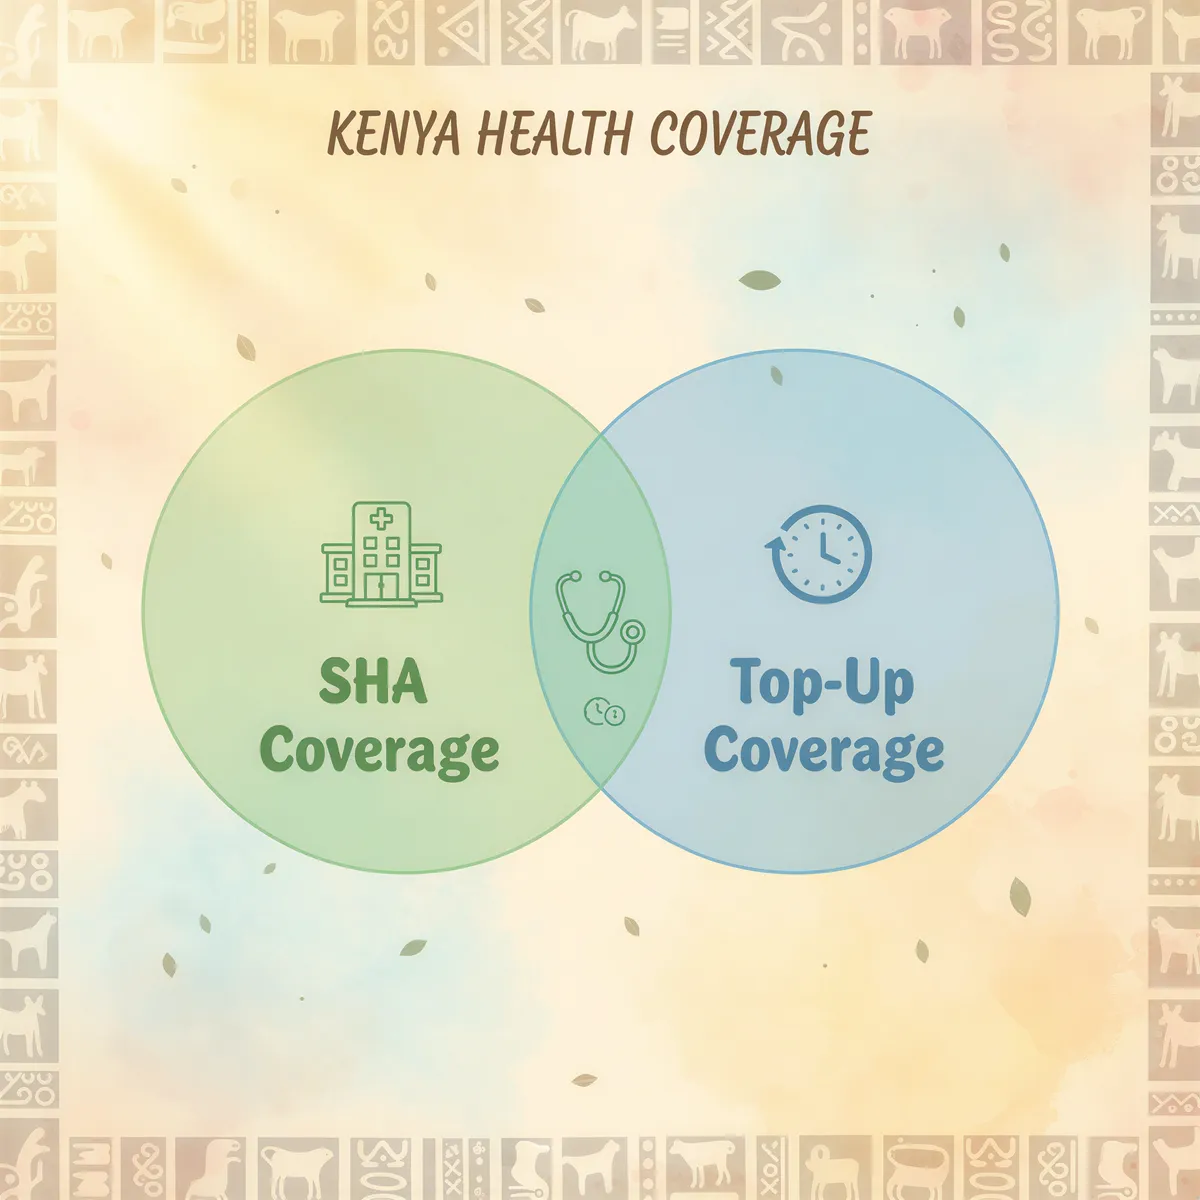
Top-ups add:
✔ Private hospitals (Nairobi Hospital, Aga Khan, MP Shah, etc.) ✔ Private rooms (no sharing) ✔ Fast service (no 6-hour queues) ✔ Specialist access (cardiologists, orthopedists, etc.) ✔ Advanced medication (beyond government formulary) ✔ Better outpatient care (private clinics) ✔ Dental & optical (optional add-ons) ✔ International emergency cover (optional)
Think of it as: SHA handles the floor. Top-up handles the ceiling.
How Much Do Top-Up Plans Cost?
Less than full private insurance.
Individual Top-Up Plans (2026 Prices)
| Age Group | Basic Top-Up | Premium Top-Up |
|---|---|---|
| 18-30 | KES 15,000 - 20,000/year | KES 30,000 - 40,000/year |
| 31-45 | KES 22,000 - 30,000/year | KES 40,000 - 55,000/year |
| 46-60 | KES 35,000 - 50,000/year | KES 60,000 - 80,000/year |
| 61-70 | KES 55,000 - 75,000/year | KES 90,000 - 120,000/year |
Family Top-Up Plans (Couple + 2 Kids)
| Coverage Level | Annual Cost |
|---|---|
| Basic | KES 35,000 - 50,000 |
| Mid-tier | KES 55,000 - 75,000 |
| Premium | KES 80,000 - 100,000 |
Why cheaper than full insurance?
SHA covers the big stuff. Top-up just fills gaps.
Types of Top-Up Plans
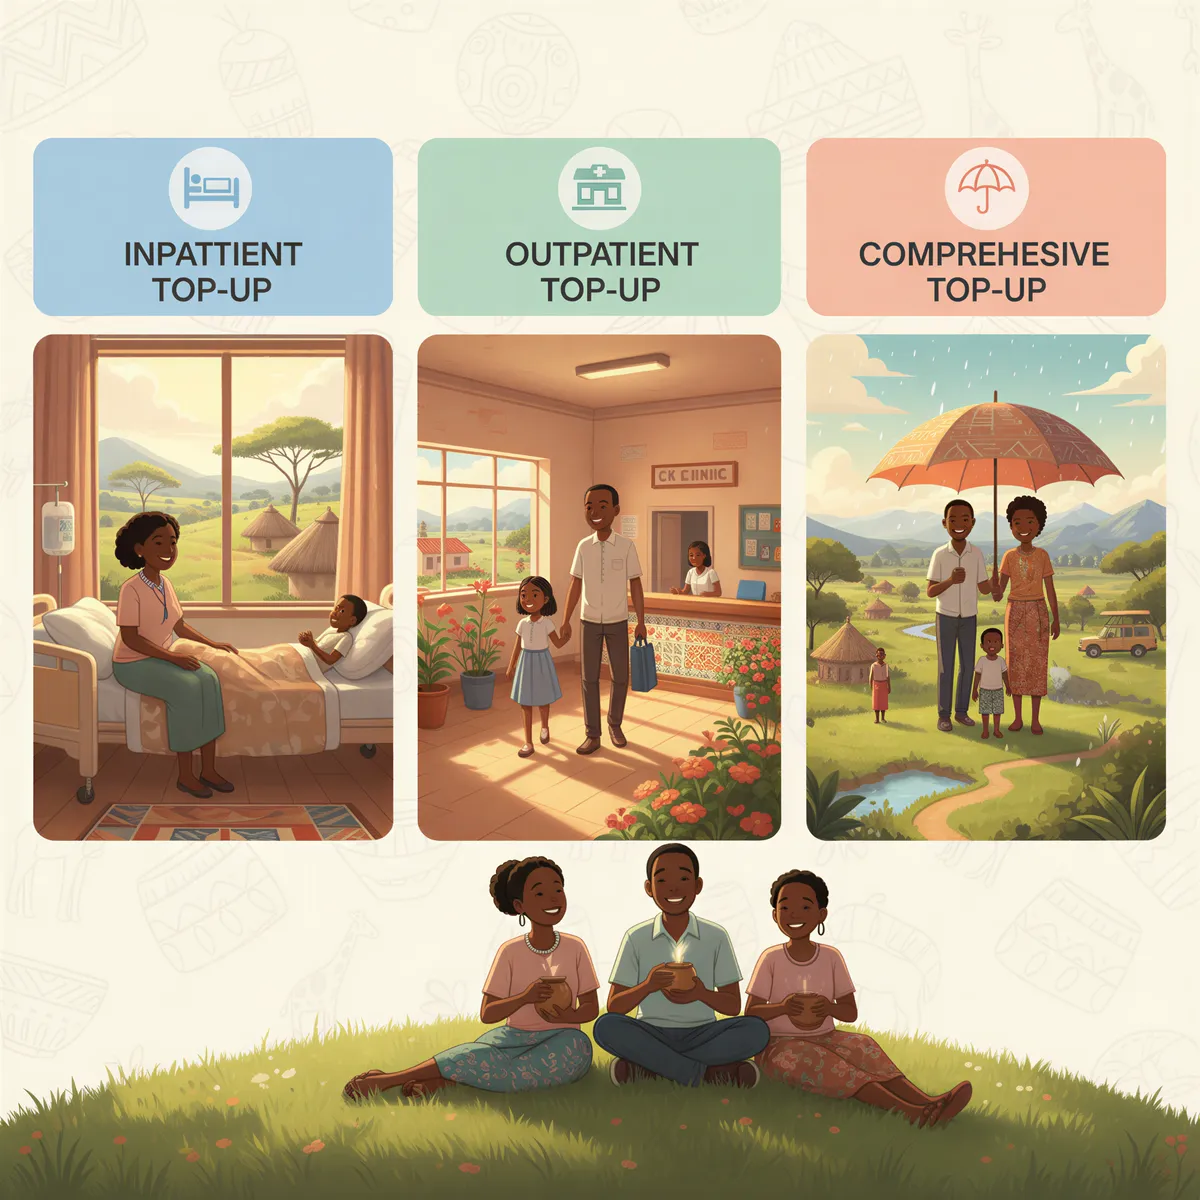
Type 1: Inpatient Top-Up Only
What it covers:
- Private hospital admission
- Surgery upgrades (private hospitals)
- ICU/HDU at private facilities
- Private room accommodation
What it doesn't:
- Outpatient care
- Dental/optical
Cost: KES 15,000 - 30,000/year Best for: Healthy people who rarely get sick
Type 2: Outpatient Top-Up Only
What it covers:
- Private clinic visits
- Lab tests at private facilities
- Prescriptions (beyond government list)
- Specialist consultations
What it doesn't:
- Hospital admission upgrades
Cost: KES 12,000 - 25,000/year Best for: Families with young kids (frequent doctor visits)
Type 3: Comprehensive Top-Up
What it covers:
- Everything (inpatient + outpatient)
- Full private hospital access
- Dental & optical (optional add-on)
Cost: KES 30,000 - 60,000/year Best for: Anyone who wants complete coverage
Best SHA Top-Up Insurance Providers
1. Britam Health (Best Value)
Top-up premium: KES 25,000 - 45,000/year (family)
Pros: ✔ Affordable pricing ✔ Good hospital network ✔ Fast claim processing ✔ Digital tools (app)
Cons: ✘ Smaller network than AAR/Jubilee
2. AAR Insurance (Best Network)
Top-up premium: KES 35,000 - 60,000/year (family)
Pros: ✔ Largest private hospital network (500+) ✔ Premium facilities ✔ Excellent service
Cons: ✘ More expensive
3. Resolution Health (Best Transparency)
Top-up premium: KES 30,000 - 50,000/year (family)
Pros: ✔ Clear pricing ✔ Great digital portal ✔ Specialist health insurer
Cons: ✘ Medium network size
4. Jubilee Health (Best for Maternity)
Top-up premium: KES 32,000 - 55,000/year (family)
Pros: ✔ Best maternity cover ✔ Large network ✔ Trusted brand
Cons: ✘ Slower pre-authorizations
How Top-Up Insurance Works (Real Example)
Scenario: Emergency appendectomy
Without Top-Up (SHA Only):
- Admitted to Kenyatta Hospital
- Shared ward (6-bed room)
- Wait time: 4-8 hours
- Basic surgery
- Government medication
- Total cost to you: KES 5,000 - 10,000 (co-payments)
With SHA + Top-Up:
- Admitted to Nairobi Hospital
- Private room
- Fast-tracked (within 1 hour)
- Advanced surgery
- Full medication range
- Total cost to you: KES 2,000 - 5,000 (co-payment)
Difference? Comfort. Speed. Quality.
Common Mistakes People Make
Mistake 1: Thinking SHA Is Enough
SHA covers emergencies. But would you want to stay in a shared ward with 6 strangers? Your choice.
Mistake 2: Buying Full Private Insurance When Top-Up Would Do
Why pay KES 80,000/year when SHA + KES 35,000 top-up gives you the same coverage?
Mistake 3: Not Understanding Co-Payments
Top-ups often have 10-20% co-payments. Factor this in.
Mistake 4: Assuming SHA Covers Private Hospitals
It doesn't. That's what the top-up is for.
Mistake 5: Skipping Outpatient Top-Up (If You Have Kids)
Kids get sick. A lot. Outpatient top-up pays for itself.
Is a Top-Up Worth It?
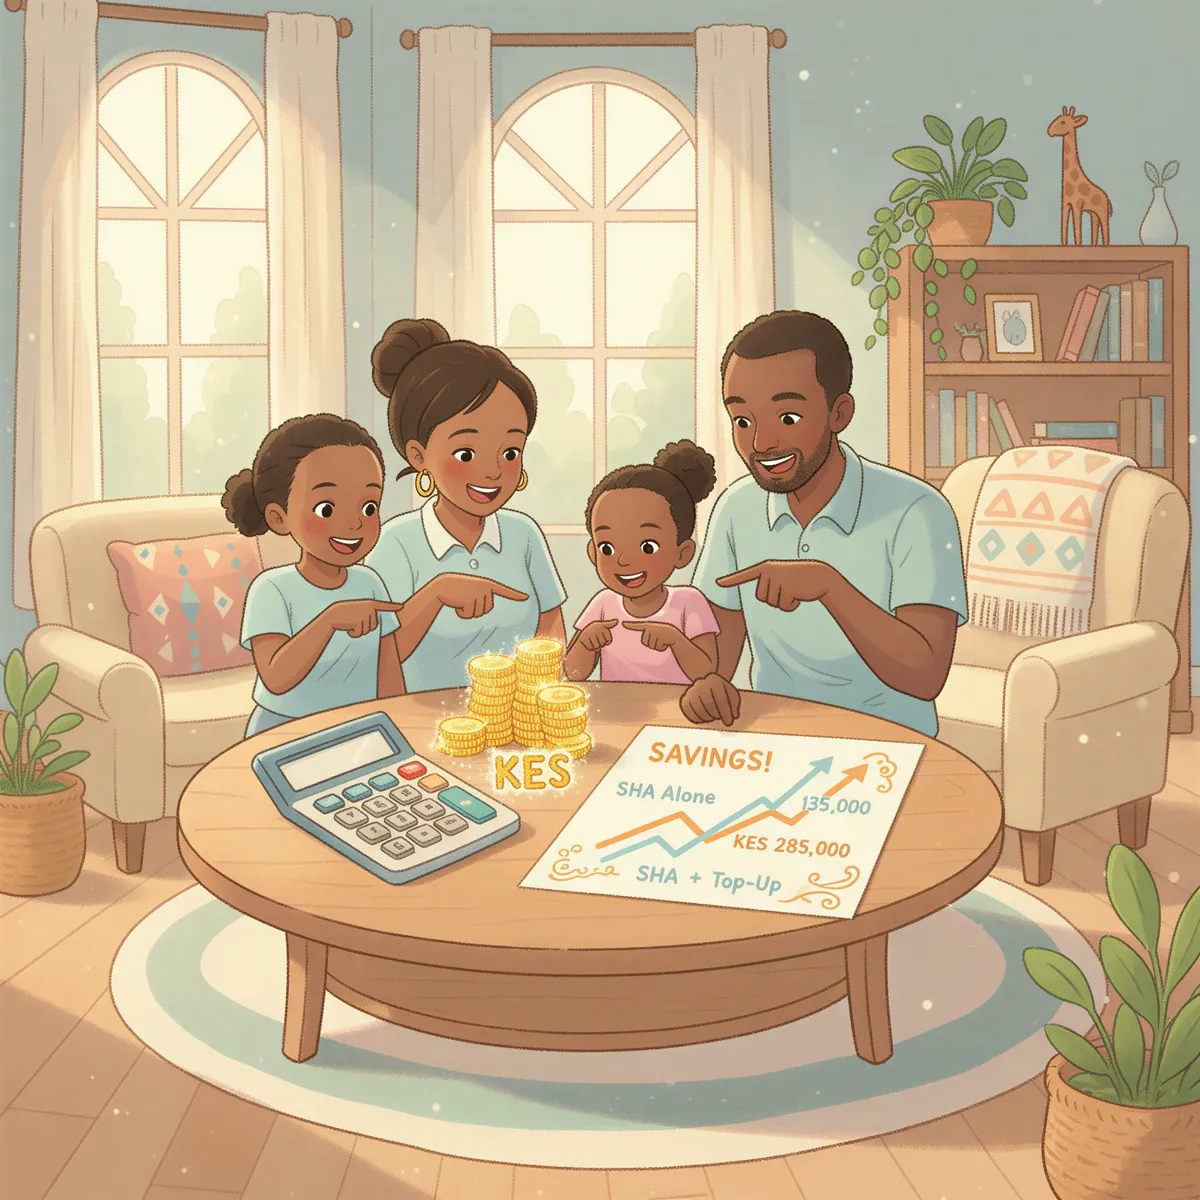
Let's do the math.
Scenario: Family of 4
SHA contribution: KES 33,000/year (mandatory, from salary)
Top-up premium: KES 45,000/year
Total annual cost: KES 78,000
What you get:
✔ Public hospital coverage (SHA) ✔ Private hospital access (top-up) ✔ Private rooms ✔ Fast service ✔ Outpatient at private clinics ✔ Wide medication access
Without top-up:
One emergency at a private hospital: KES 150,000 - 300,000 out of pocket.
With top-up:
Same emergency: KES 5,000 - 15,000 co-payment.
Savings: KES 135,000 - 285,000
Verdict: Absolutely worth it.
What Top-Ups DON'T Cover
Still excluded:
✘ Cosmetic surgery ✘ Experimental treatments ✘ Self-inflicted injuries ✘ Some pre-existing conditions (12-month waiting) ✘ Elective procedures without medical need
Same exclusions as regular insurance.
Can You Have Multiple Top-Ups?
Technically yes. Practically no.
You can't claim the same expense twice.
Example:
- Top-up A covers KES 100,000
- Top-up B covers KES 100,000
- Your bill: KES 120,000
You can't claim KES 120,000 from both.
You claim from one. Lose the other premium.
Not worth it. Stick to one top-up.
How to Buy a SHA Top-Up Plan
Step 1: Confirm Your SHA Contribution
Check your payslip. SHA should be deducted (2.75% of gross salary).
Step 2: Assess Your Needs
Ask:
- Do I visit private hospitals?
- Do my kids get sick often?
- Can I afford to pay out of pocket for private care?
Step 3: Get Quotes from 3-4 Insurers
Submit:
- Your age
- Family size
- Preferred coverage (inpatient, outpatient, or both)
Step 4: Compare
Look at:
- Premium cost
- Hospital network
- Co-payment percentage
- Exclusions
Step 5: Buy
Apply online or through an agent.
You'll need:
- ID
- SHA number
- Payment method (M-Pesa, bank transfer)
Step 6: Get Your Insurance Card
Digital or physical. Use it at private hospitals.
Do You Need Outpatient Top-Up?
It depends.
You NEED it if:
- You have young kids (they get sick 5-10 times/year)
- You have a chronic condition (diabetes, hypertension)
- You prefer private clinics over government facilities
You DON'T need it if:
- You're young and healthy
- You can afford KES 3,000 - 5,000 per doctor visit out of pocket
- You're okay with government clinics
Rule of thumb: If you visit a doctor 3+ times/year, outpatient top-up pays for itself.
SHA vs Private Insurance vs Top-Up: Final Comparison
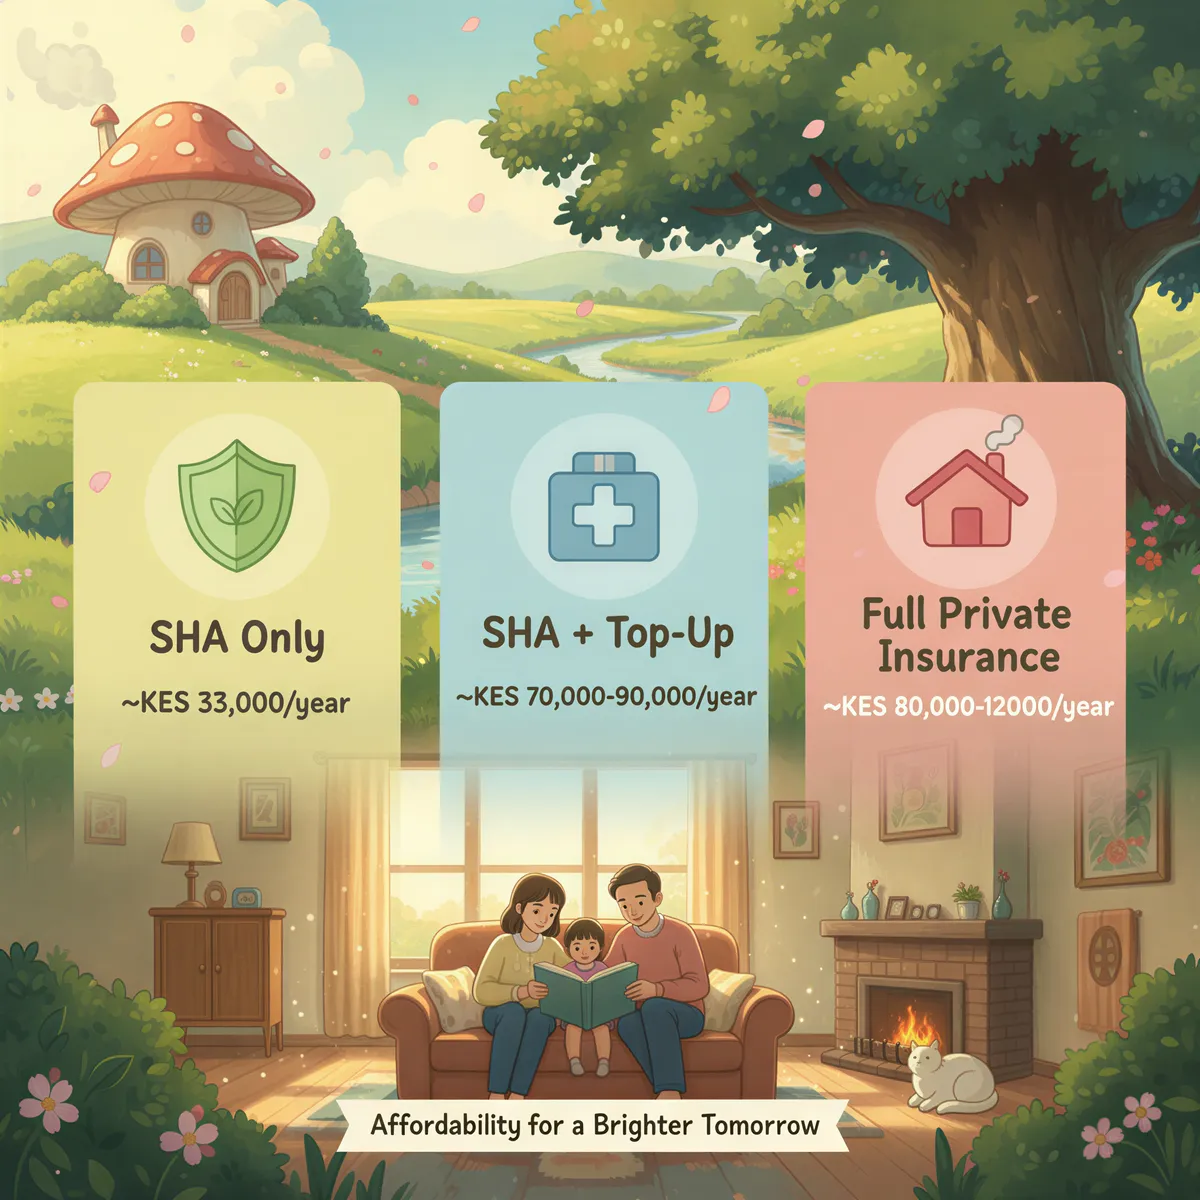
| Feature | SHA Only | Full Private Insurance | SHA + Top-Up |
|---|---|---|---|
| Cost | KES 33,000/year | KES 80,000 - 120,000/year | KES 70,000 - 90,000/year |
| Private hospitals | ✘ | ✔ | ✔ |
| Private rooms | ✘ | ✔ | ✔ |
| Fast service | ✘ | ✔ | ✔ |
| Outpatient | Government clinics only | ✔ | ✔ |
| Best for | Tight budgets | Maximum comfort | Best value |
Winner: SHA + Top-Up (best balance of cost and coverage)
What If Your Employer Provides Group Insurance?
Lucky you.
Here's what happens:
If employer insurance is comprehensive, you don't need a top-up.
If employer insurance is basic (inpatient only), add an outpatient top-up.
Pro tip: Ask HR:
- What does our group insurance cover?
- Is outpatient included?
- What's the hospital network?
Then decide if you need additional cover.
Can You Cancel Your Top-Up?
Yes, but...
No refunds for unused months.
Example:
- Pay KES 36,000 annual premium in January
- Cancel in June
- No refund
Better strategy: Let it expire at renewal. Don't renew.
Top-Up for Seniors (60+ Years)
Costs more. But still valuable.
Typical senior top-up: KES 60,000 - 100,000/year
Why it's worth it:
- Seniors use healthcare more
- Private hospitals provide better senior care
- Government facilities can be overwhelming
Best insurers for senior top-ups:
- ICEA Lion
- Jubilee
- AAR
Next Steps
- Check your SHA status (are you contributing?)
- Assess your healthcare usage
- Get quotes from Britam, AAR, Resolution, Jubilee
- Compare:
- Premium cost
- Hospital network
- Co-payments
- Buy the best fit
- Use it when you need private care
SHA is great.
But it's basic.
If you want comfort, speed, and choice?
Add a top-up.
Your health (and wallet) will thank you.
Start Generating Quotes in Minutes
Compare quotes from Kenya's leading insurers and send a client a proposal in under a minute.
No credit card required.
Get quotes from 40+ underwriters in under 30 seconds.
All quotes meet Insurance Regulatory Authority standards.
Never miss a commission payment with automatic tracking.