Senior Health Insurance Kenya: 6 Plans That Accept Over-70s
My 67-year-old father tried to buy health insurance last year.
First insurer: "Sorry, age limit is 65."
Second insurer: "KES 180,000/year. Take it or leave it."
Third insurer: "Medical exam required. Then we'll decide."
Finding health insurance after 60 in Kenya? It's tough.
But not impossible.
Here's how seniors can get covered without breaking the bank.
Table of Contents
- The Senior Insurance Challenge
- What Age Is Considered "Senior" for Insurance?
- How Much Does Senior Health Insurance Cost?
- Best Health Insurers for Seniors
- What Senior Health Insurance Covers
- Medical Underwriting for Seniors (Expect This)
- Pre-Existing Conditions (The Big Issue)
- Can You Get Insurance After 70?
- SHA (Social Health Authority) for Seniors
- Senior-Specific Health Plans
- How to Save Money on Senior Insurance
- What If You're Rejected?
- Chronic Disease Management Programs
- Last Expense Cover (Important for Seniors)
- Can You Add Your Elderly Parents to Your Policy?
- Renewal Challenges for Seniors
- International Emergency Cover (For Frequent Travelers)
- Real Senior Case Studies
- Senior Health Insurance Myths (Debunked)
- Next Steps for Seniors
The Senior Insurance Challenge
Reality check:
Most health insurers in Kenya don't want senior customers.
Why?
- Higher risk of illness
- More frequent claims
- Chronic conditions (diabetes, hypertension, etc.)
- Expensive treatments
Result: Higher premiums, stricter requirements, or outright rejection.
But some insurers specialize in seniors. Let's find them.
What Age Is Considered "Senior" for Insurance?
Here's the thing nobody explains properly: entry age and renewal age are two different numbers. Mixing them up is the single most common mistake in senior insurance, and it costs people real money.
- Entry age is the oldest you can be when you first buy the policy.
- Renewal age is how long you can keep it once you're in.
A brochure that shows premium rates for a 70-year-old does not mean a 70-year-old can buy that plan. Those rate bands are usually there for existing members renewing. Buy at 60, renew for life. Show up at 70 asking to join, and you get declined.
Entry ages we've verified from the actual underwriter brochures:
| Product | Entry age | Notes |
|---|---|---|
| AAR ShwAARi | 0 - 100 | Budget cover, outpatient bundled |
| AAR Seniors CAARe | 65 - 85 | Senior-specific, family-shared inpatient |
| APA Jamii Plus | 21 - 80 | No senior-product transition needed |
| Old Mutual Seniors | 65 - 80 | Lifetime renewal once enrolled |
| Old Mutual Executive | 19 - 80 | Premium tier, 10M-20M limits |
| Jubilee J Senior | 65 - 79 | Senior-specific |
| Old Mutual AfyaImara Family / County | 19 - 65 | Not a senior product |
| Jubilee CoverBora | 0 - 65 | Not a senior product |
| Heritage HeriAfya | 18 - 65 | Not a senior product |
| AAR Family / Individual | 0 - 64 | Not a senior product |
| Jubilee JCare | 18 - 64 | Not a senior product |
Read that bottom half again. AAR Individual, Jubilee JCare and Old Mutual AfyaImara Family all publish rate tables that run past 65. None of them will accept you as a new member at 66. The rates are for people already on the book.
So what actually changes at 60? Not much, legally. What changes is pricing: most rate bands step up at 51, again at 65, and again at 70-75. The cutoffs that matter are 64/65 (you fall off the mainstream products) and 80 (you fall off almost everything except ShwAARi).
Other insurers (ICEA Lion, Britam, Madison, Resolution) run senior products too. We haven't verified their brochures line by line yet, so we're not going to quote you numbers we can't stand behind. Ask your agent for the entry age in writing.
How Much Does Senior Health Insurance Cost?
Real 2026 prices:
Individual Senior Plans (60-70 years)
| Coverage Type | Annual Premium |
|---|---|
| Inpatient only | KES 70,000 - 100,000 |
| Inpatient + Outpatient | KES 110,000 - 150,000 |
| Full package | KES 140,000 - 180,000 |
Senior Couple (Both 60-70)
| Coverage Type | Annual Premium |
|---|---|
| Inpatient only | KES 130,000 - 170,000 |
| Inpatient + Outpatient | KES 180,000 - 230,000 |
| Full package | KES 220,000 - 280,000 |
Sticker shock? Yeah. Senior insurance is 2-3x more expensive than coverage for 30-year-olds.
Best Health Insurers for Seniors
We've stopped ranking these 1-4. The old order was built on entry ages that turned out to be wrong once we checked the brochures directly, and AAR in particular was rated down on a cutoff of 65 that doesn't exist. Compare on the verified entry ages first, then on network and price.
ICEA Lion
Max entry age: 75 (not yet brochure-verified by us) Annual premium (70-year-old): KES 120,000 - 160,000
Why they're best: ✔ Long track record with senior applicants ✔ Experience with senior care ✔ Good hospital network ✔ Stable company
Cons: ✘ Higher premiums ✘ Slower digital experience
Jubilee Health Insurance
Max entry age: 79 (J Senior; JCare closes at 64) Annual premium (65-year-old): KES 110,000 - 140,000
Why they're good: ✔ Best maternity (if you have daughters/daughters-in-law to cover) ✔ Large hospital network ✔ Reliable claims
Cons: ✘ Premium pricing
Madison Insurance
Max entry age: 70 (not yet brochure-verified by us) Annual premium (65-year-old): KES 100,000 - 130,000
Why they're good: ✔ Specialize in chronic conditions ✔ Flexible underwriting ✔ Lower premiums than Jubilee/AAR
Cons: ✘ Medium network
AAR Insurance
Max entry age: 85 (Seniors CAARe), or 100 on ShwAARi Annual premium (64-year-old): KES 120,000 - 150,000
Why they're good: ✔ Largest hospital network ✔ Premium facilities ✔ Good senior care
Cons: ✘ Won't accept you after 65 ✘ Expensive
What Senior Health Insurance Covers
Standard coverage:
✔ Inpatient: Hospital admission, surgery, ICU ✔ Outpatient: Doctor visits, medication, lab tests ✔ Chronic disease management: Diabetes, hypertension checkups ✔ Emergency care ✔ Specialist consultations
Common exclusions for seniors:
✘ Pre-existing conditions (12-24 month waiting periods) ✘ Experimental treatments ✘ Cosmetic procedures ✘ Dental implants (basic dental okay)
Medical Underwriting for Seniors (Expect This)
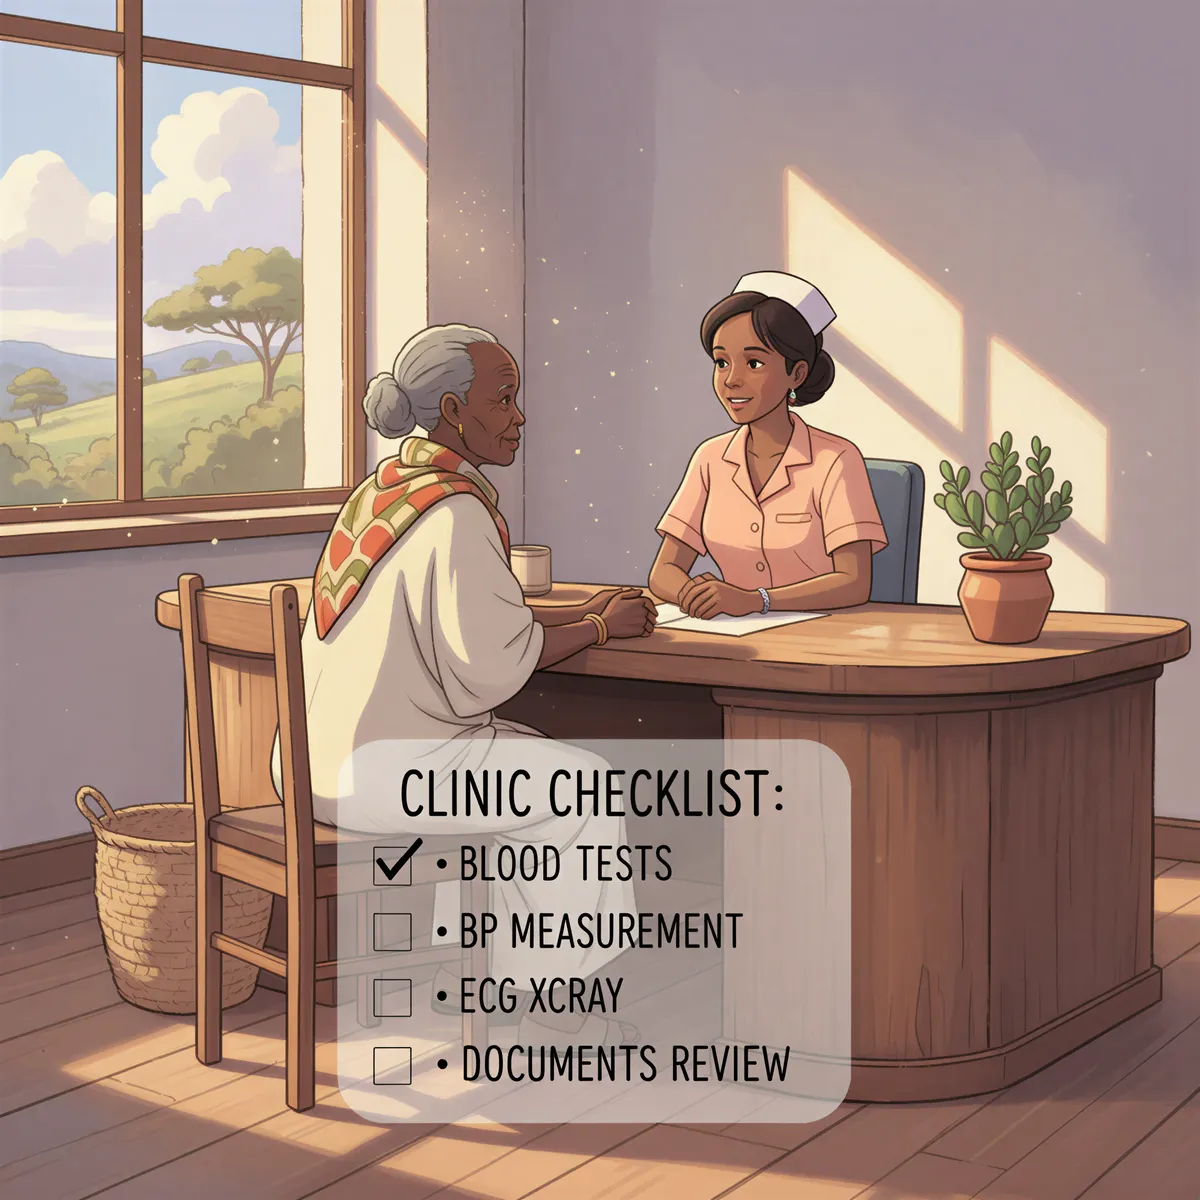
Unlike younger people, seniors usually need:
- Detailed medical questionnaire
- Medical exam (blood tests, BP check, ECG, sometimes chest X-ray)
- Doctor's report (if you have chronic conditions)
- Medication list
Insurers want to know:
- Current health status
- Chronic conditions
- Medications
- Recent hospitalizations
Be honest. Lying = claim rejection later.
Pre-Existing Conditions (The Big Issue)
Most seniors have at least one:
- Hypertension
- Diabetes
- Arthritis
- Heart disease
- Prostate issues (men)
How insurers handle it:
Option A: Accept with 12-24 month waiting period Option B: Accept with higher premium (+30-50%) Option C: Exclude that condition permanently Option D: Reject application
Best strategy: Apply to multiple insurers. Each has different underwriting.
Can You Get Insurance After 70?
Yes. More easily than most agents will tell you.
The "you can't get cover after 70" line is usually an agent who only sells two or three products and has never checked the rest. Here's what a 72-year-old can actually enter today, straight off the brochures:
| Product | Entry age | Fits a 72-year-old? |
|---|---|---|
| AAR ShwAARi | 0 - 100 | Yes |
| AAR Seniors CAARe | 65 - 85 | Yes |
| Old Mutual Seniors | 65 - 80 | Yes |
| APA Jamii Plus | 21 - 80 | Yes |
| Old Mutual Executive | 19 - 80 | Yes |
| Jubilee J Senior | 65 - 79 | Yes |
Six products. Not one.
A worked example. A 75-year-old wanting 3M inpatient plus 150K outpatient gets a genuine four-way comparison: AAR Seniors CAARe, APA Jamii Plus, Jubilee J Senior and Old Mutual AfyaImara Seniors. Every one of those accepts entry at 75. Old Mutual AfyaImara Family does not, even though its rate card shows a 66+ band, because entry closes at 65.
The one number that ends the conversation: 85
Past 85, AAR ShwAARi is effectively the last door open, and it's a budget cover. Between 80 and 85 you're down to AAR Seniors CAARe. That's the real cliff, not 70.
Option 2: Continue Existing Policy
If you already have cover, most insurers let you renew indefinitely. Old Mutual Seniors explicitly guarantees lifetime renewal once you're enrolled.
Never let your policy lapse after 70. A lapse turns you back into a new applicant, and new applicants get judged on entry age. That's how a 71-year-old with fifteen unbroken years of cover ends up uninsurable over one missed payment.
Option 3: Group Insurance (If Available)
Some employers and associations offer group plans that accept 70+, usually without individual underwriting. Worth asking about SACCO and professional-body schemes.
Option 4: SHA Only
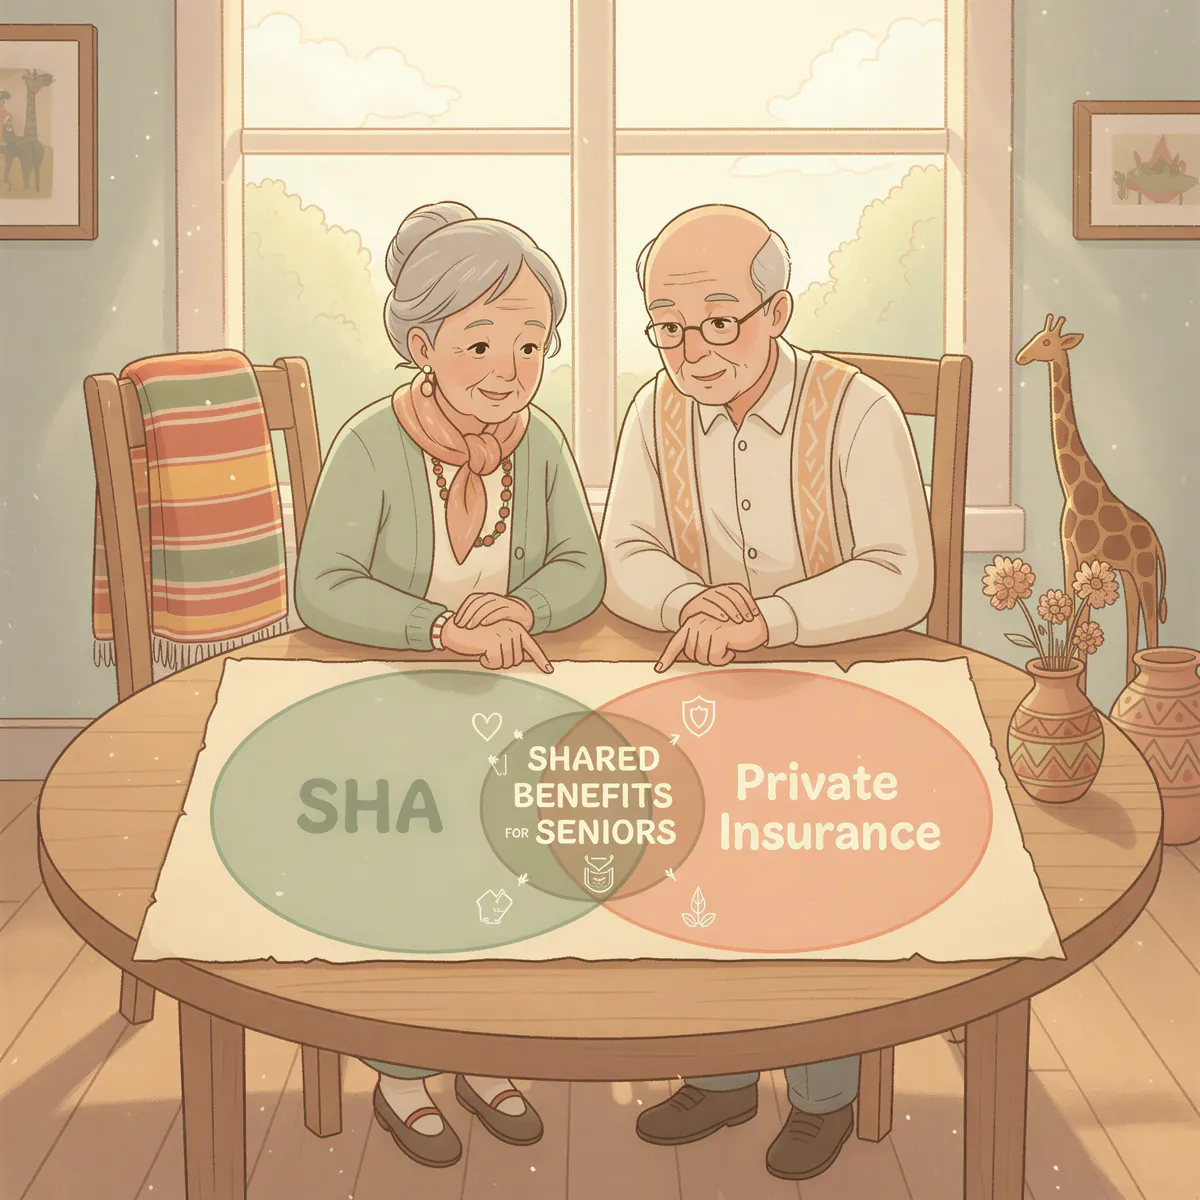
SHA covers everyone, any age. Public hospitals only, but better than nothing, and it works alongside a private plan rather than instead of one.
SHA (Social Health Authority) for Seniors
SHA is mandatory and covers:
✔ Public hospital care ✔ Inpatient services ✔ Basic medication ✔ Chronic disease management (at government facilities)
Cost: 2.75% of pension/income (or fixed rate for pensioners)
Limitations: ✘ Long queues ✘ Shared wards ✘ Limited medication options ✘ No private hospitals
Best strategy: SHA + private insurance = complete coverage.
Senior-Specific Health Plans
Some insurers offer senior-focused plans:
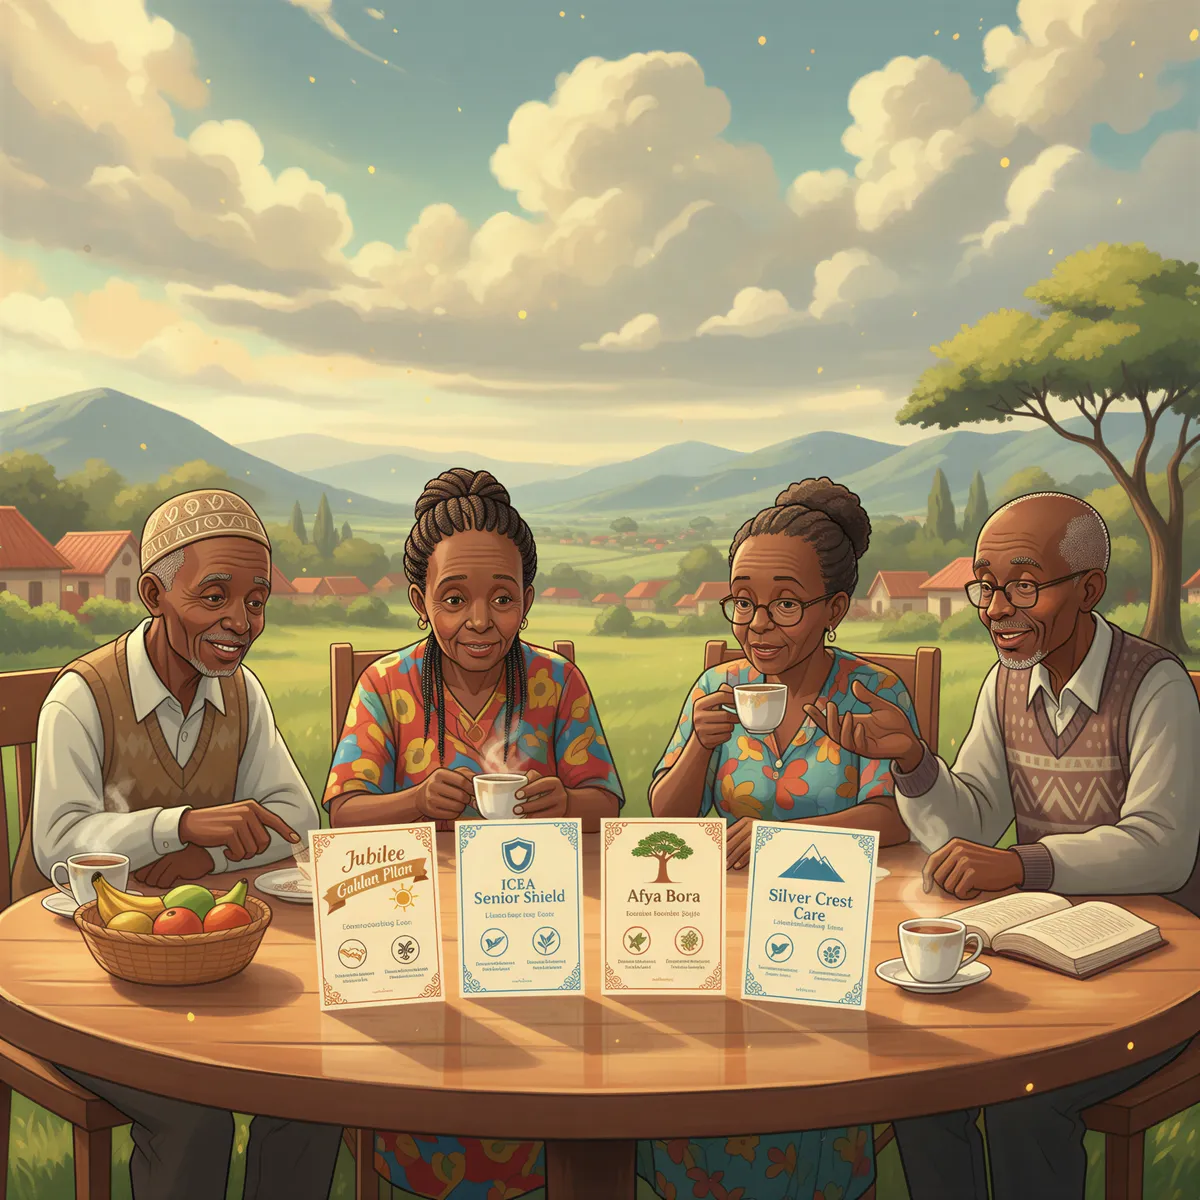
Jubilee Golden Plan
Age: 60-70 Features:
- Simplified underwriting
- Chronic disease management
- Annual health checkups included
Premium: KES 120,000 - 150,000/year
ICEA Senior Shield
Age: 60-75 Features:
- Accepts older seniors
- Focus on inpatient care
- Last expense cover included
Premium: KES 130,000 - 180,000/year
How to Save Money on Senior Insurance
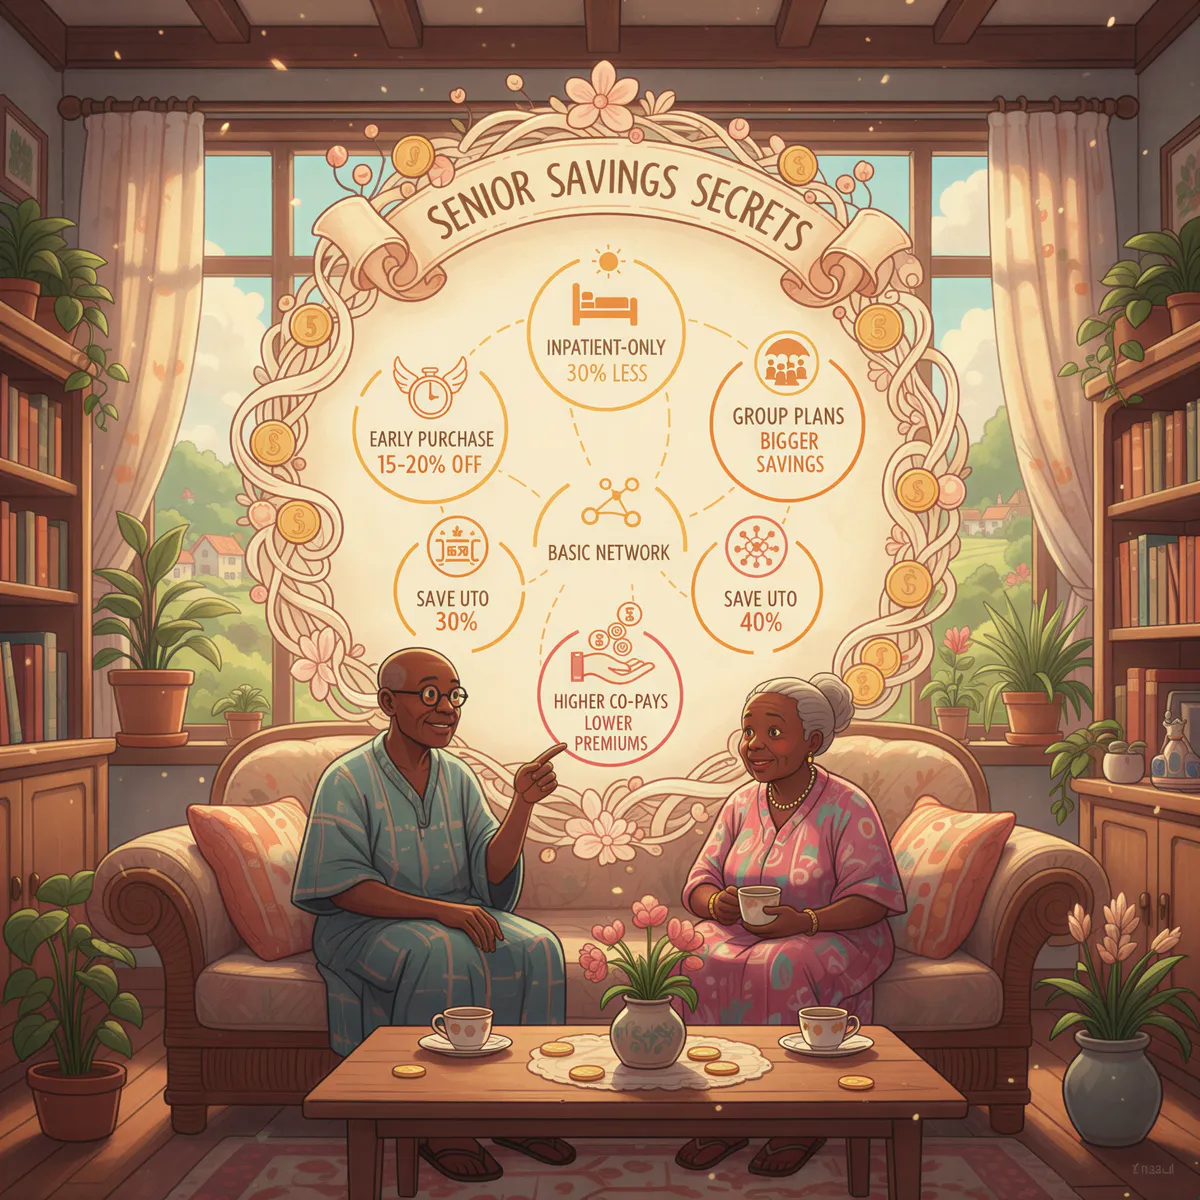
Tip 1: Buy Before 60
Premiums jump at 60. Lock in rates at 55-59.
Tip 2: Choose Inpatient-Only
Skip outpatient if you can afford doctor visits out-of-pocket.
Savings: 30-40%
Tip 3: Higher Co-Payments
Agree to pay 20-30% of claims yourself.
Premium reduction: 15-25%
Tip 4: Basic Hospital Network
Skip premium hospitals. Stick to mid-tier.
Savings: 20-30%
Tip 5: Join Group Plan
Church groups, retiree associations often offer group rates.
Savings: 30-40% vs individual
What If You're Rejected?
Don't give up.
Options:
1. Try Different Insurers
Madison might accept what AAR rejected.
2. Negotiate Exclusions
"Exclude my diabetes. Cover everything else."
3. Join Group Plan
Associations, SACCOs, church groups.
4. Get Inpatient-Only with Exclusions
Better than nothing.
5. Focus on SHA + Out-of-Pocket
Not ideal, but manageable.
Chronic Disease Management Programs
Some insurers offer:
✔ Free quarterly checkups ✔ Medication reminders ✔ Health coaching ✔ Discounted medication ✔ Home care (some plans)
Best insurers for this:
- Madison
- Resolution
- AAR
Last Expense Cover (Important for Seniors)
Many senior plans include burial insurance.
Typical payout: KES 100,000 - 500,000
Covers:
- Funeral expenses
- Burial costs
- Transport of remains
Worth it? Yes. Relieves family burden.
Can You Add Your Elderly Parents to Your Policy?
Yes, but expensive.
How it works:
You have family health insurance. Add your 70-year-old mother as a dependent.
Cost: +KES 80,000 - 120,000/year (on top of your premium)
Most insurers allow:
- Parents up to 70-75 years
- Requires medical exam
- Pre-existing conditions waiting periods
Cheaper than individual policy? Slightly (10-15%).
Renewal Challenges for Seniors
Expect:
- Higher premium increases (15-25% annually vs 10-15% for younger)
- More stringent medical reviews
- Possible exclusions added (based on claims)
What to do:
- Shop around at renewal
- Negotiate
- Show good health management
Never let policy lapse. Re-entry after 70 is nearly impossible.
International Emergency Cover (For Frequent Travelers)
Some senior plans include:
✔ Emergency medical evacuation ✔ Treatment abroad (up to limits) ✔ Repatriation of remains
Insurers offering this:
- GA Insurance
- AAR (premium plans)
- Jubilee (premium plans)
Worth it? Only if you travel 3+ times/year internationally.
Real Senior Case Studies
Case 1: John, 66, Hypertension
Challenge: AAR rejected (over 65)
Solution:
- Applied to ICEA Lion
- Medical exam showed well-controlled BP
- Accepted with 12-month waiting for hypertension
- Premium: KES 125,000/year
Outcome: Now fully covered. Happy with service.
Case 2: Mary, 72, Diabetes + Arthritis
Challenge: Too old for most insurers
Solution:
- Joined church group plan
- Group accepted her (no individual underwriting)
- Premium: KES 95,000/year
Outcome: Best option at her age.
Case 3: Peter, 68, Multiple Conditions
Challenge: Rejected by 4 insurers
Solution:
- Bought inpatient-only (excluded all pre-existing)
- Covers accidents, new illnesses
- Uses SHA for chronic condition management
Outcome: Not perfect, but manages.
Senior Health Insurance Myths (Debunked)
Myth 1: "You can't get insurance after 65"
False. AAR Seniors CAARe takes entry to 85. Old Mutual Seniors and APA Jamii Plus to 80. Jubilee J Senior to 79. AAR ShwAARi to 100.
Myth 2: "It's too expensive, not worth it"
False. One hospitalization = KES 200,000+. Insurance pays for itself.
Myth 3: "Pre-existing conditions mean automatic rejection"
False. Many insurers cover pre-existing after waiting periods.
Myth 4: "SHA is enough"
False. SHA = public hospitals only. Long waits. Basic care.
Next Steps for Seniors
- Ask for the entry age in writing (not the rate table, the entry age)
- Start before 65 if you can, when you still have the full market
- Get a medical checkup so you know your health status before you apply
- Compare the senior products side by side (AAR Seniors CAARe, APA Jamii Plus, Jubilee J Senior, Old Mutual Seniors)
- Disclose everything honestly
- Price dental and optical separately if you want them, they're rarely bundled on senior plans
- Never let the policy lapse
Age is not a barrier.
It's harder. It's more expensive.
But it's possible.
And worth it.
Start Generating Quotes in Minutes
Compare quotes from Kenya's leading insurers and send a client a proposal in under a minute.
No credit card required.
Get quotes from 40+ underwriters in under 30 seconds.
All quotes meet Insurance Regulatory Authority standards.
Never miss a commission payment with automatic tracking.