Health Insurance for the Self-Employed in Kenya
No employer health insurance.
No group rates.
No subsidies.
Welcome to self-employment.
I'm a freelancer. Been there. Paid KES 60,000/year for insurance that would cost an employee KES 20,000.
But here's what I learned:
Self-employed Kenyans CAN get affordable health insurance.
You just need to know how.
Table of Contents
- The Self-Employed Insurance Challenge
- How Much Does Health Insurance Cost for Self-Employed?
- Strategy 1: Join a Professional Association (Get Group Rates)
- Strategy 2: Use SHA + Private Top-Up (Best Value)
- Strategy 3: Form Your Own Group (Chama/SACCO)
- Strategy 4: Choose Inpatient-Only (Big Savings)
- Strategy 5: Negotiate Higher Co-Payments (Lower Premiums)
- Strategy 6: Buy During Enrollment Periods (Avoid Loading)
- Strategy 7: Bundle with Other Insurance (Get Discounts)
- Best Health Insurers for Self-Employed
- Tax Deductions for Self-Employed
- What If You Have Irregular Income?
- Can You Deduct Premiums as Business Expense?
- What About Maternity (If You're Planning a Family)?
- Handling Renewals (Premium Increases)
- Red Flags: Insurers to Avoid
- Common Mistakes Self-Employed Make
- Real Case Studies
- Your Action Plan
- Next Steps
The Self-Employed Insurance Challenge
Reality check:
Employees get:
- Employer pays 50-100% of premium
- Group rates (30-40% cheaper)
- No medical exams
- Automatic approval
Self-employed get:
- Pay 100% yourself
- Individual rates (expensive)
- Medical questionnaires
- Possible rejection
Fair? No. Reality? Yes.
But don't worry. There are ways to beat the system.
How Much Does Health Insurance Cost for Self-Employed?
Real 2026 prices (individual plans):
Age 25-35
| Coverage | Annual Cost | Monthly |
|---|---|---|
| Inpatient only | KES 20,000 - 30,000 | KES 1,700 - 2,500 |
| Inpatient + Outpatient | KES 40,000 - 55,000 | KES 3,300 - 4,600 |
| Full package | KES 50,000 - 65,000 | KES 4,200 - 5,400 |
Age 36-45
| Coverage | Annual Cost | Monthly |
|---|---|---|
| Inpatient only | KES 35,000 - 50,000 | KES 2,900 - 4,200 |
| Inpatient + Outpatient | KES 55,000 - 75,000 | KES 4,600 - 6,250 |
| Full package | KES 70,000 - 90,000 | KES 5,800 - 7,500 |
Age 46-55
| Coverage | Annual Cost | Monthly |
|---|---|---|
| Inpatient only | KES 55,000 - 75,000 | KES 4,600 - 6,250 |
| Inpatient + Outpatient | KES 85,000 - 115,000 | KES 7,100 - 9,600 |
| Full package | KES 110,000 - 140,000 | KES 9,200 - 11,700 |
Ouch. Yeah, it's expensive.
But read on. I'll show you how to cut these costs by 30-50%.
Strategy 1: Join a Professional Association (Get Group Rates)
This is THE hack.
How it works:
Professional associations negotiate group rates with insurers.
You join the association. Get access to group insurance.
Examples:
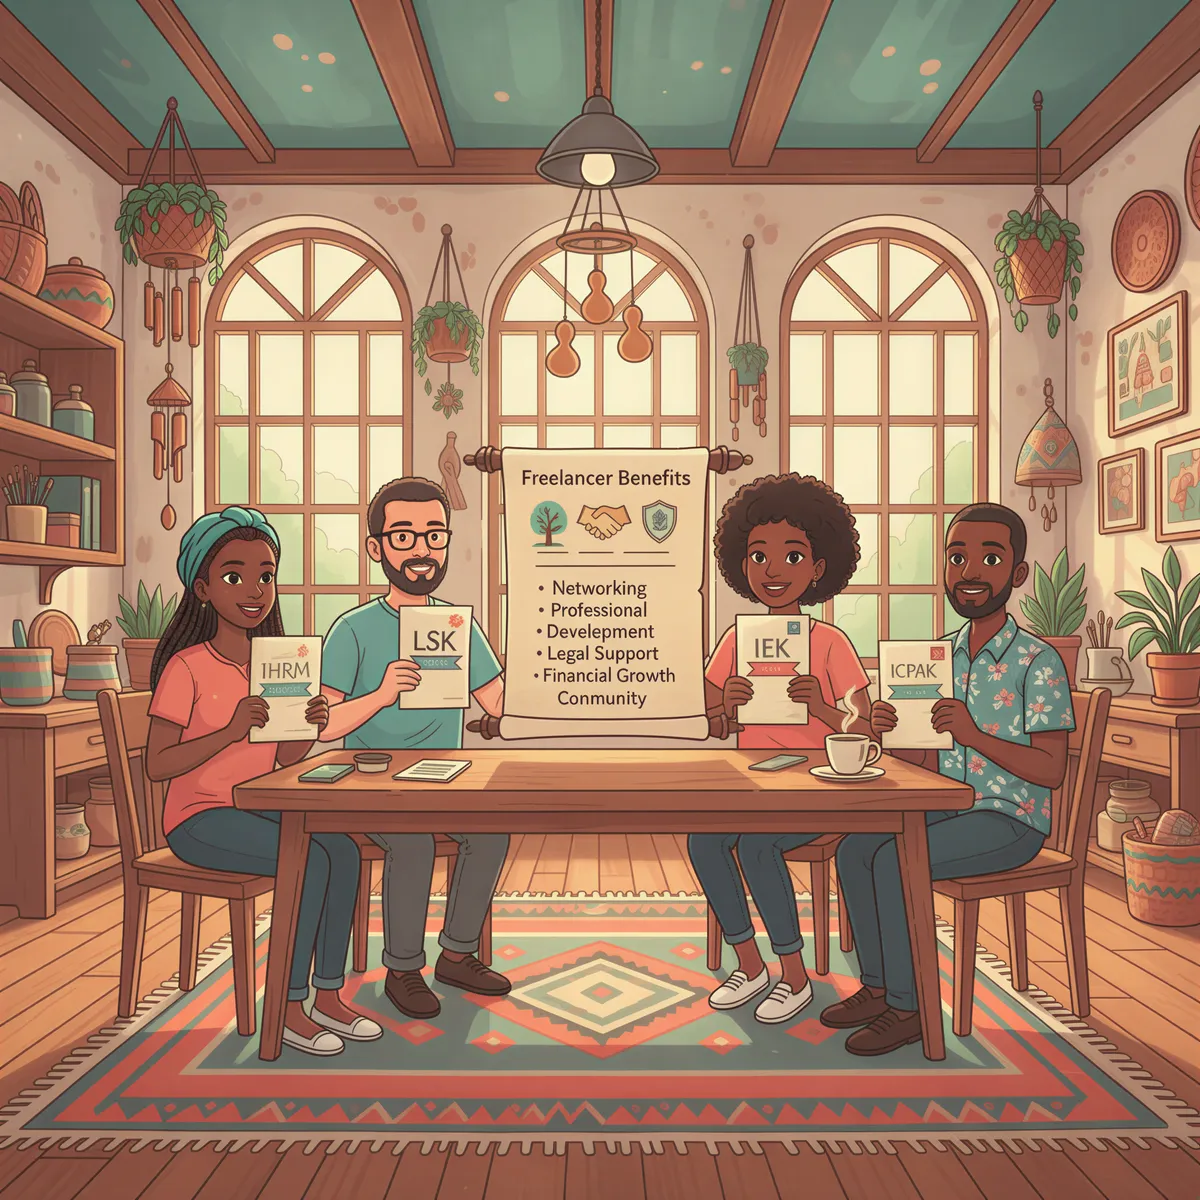
IHRM (Institute of Human Resource Management)
- Member fee: KES 15,000/year
- Health insurance discount: 30-40%
- Break-even: If you save KES 15,000+ on insurance, it's worth it
LSK (Law Society of Kenya)
- For lawyers
- Group health insurance available
- Significant discounts
IEK (Institution of Engineers of Kenya)
- For engineers
- Group rates with multiple insurers
ICPAK (Institute of Certified Public Accountants)
- For accountants
- Affordable group plans
Freelancers Association of Kenya
- Open to all freelancers
- Pooled insurance rates
Pro tip: Even if you're not in these professions, some associations accept "associate members."
Savings: KES 15,000 - 30,000/year
Strategy 2: Use SHA + Private Top-Up (Best Value)
Instead of full private insurance:
Option A: Full private insurance (KES 60,000/year)
Option B: SHA (KES 33,000/year) + Top-up (KES 25,000/year) = KES 58,000
Option B covers:
- Public hospitals via SHA
- Private hospitals via top-up
- Same coverage as Option A
Savings: KES 2,000 - 20,000/year (depending on plan)
Bonus: SHA contributions reduce your taxable income.
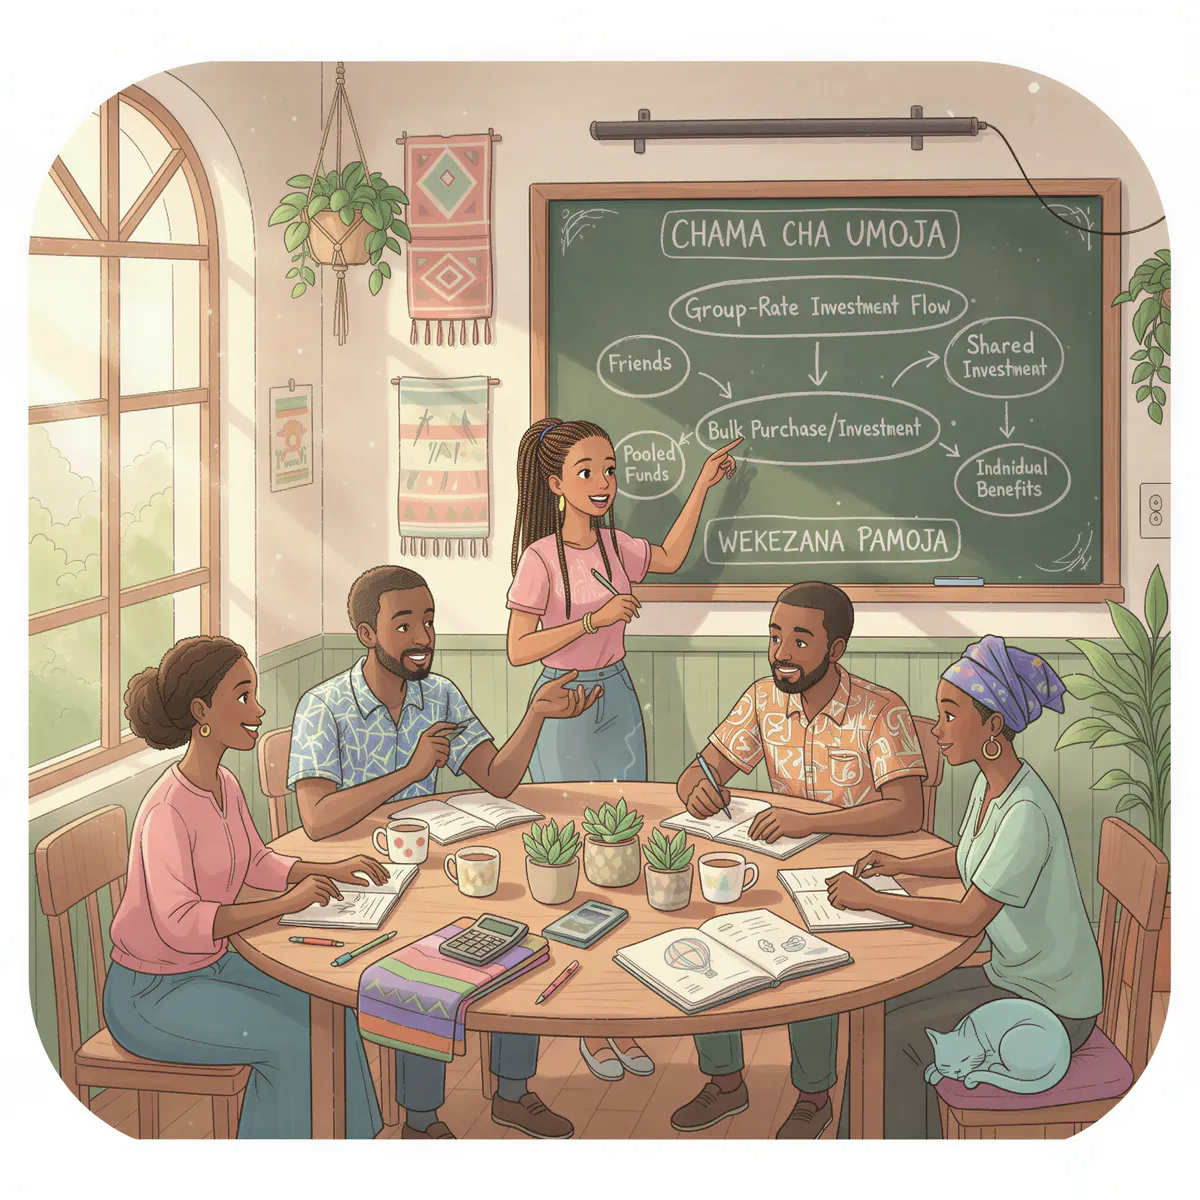
Strategy 3: Form Your Own Group (Chama/SACCO)
Minimum group size: 5-10 members (depends on insurer)
How it works:
- Find 5-10 self-employed friends/colleagues
- Form informal group (or chama)
- Apply for group health insurance
- Each member pays their share
- Everyone gets group rates
Example:
Individual rates:
- 10 freelancers
- KES 50,000/person/year
- Total: KES 500,000
Group rates:
- Same 10 freelancers
- KES 35,000/person/year
- Total: KES 350,000
Savings: KES 150,000 total (KES 15,000/person)
Best insurers for small groups:
Strategy 4: Choose Inpatient-Only (Big Savings)
If you're healthy and rarely visit doctors:
Skip outpatient. Focus on emergency cover.
Comparison:
| Plan | Annual Cost |
|---|---|
| Inpatient + Outpatient | KES 55,000 |
| Inpatient only | KES 25,000 |
| Savings | KES 30,000 |
When this works:
- You're young and healthy
- You can afford KES 3,000-5,000 for occasional doctor visits
- You prioritize emergency/surgery cover
When this doesn't work:
- You have chronic conditions (diabetes, hypertension)
- You have young kids (they get sick often)
- You visit doctors 5+ times/year
Strategy 5: Negotiate Higher Co-Payments (Lower Premiums)
How co-payments work:
0% co-payment plan:
- Insurer pays 100% of bills
- Premium: KES 55,000/year
20% co-payment plan:
- You pay 20% of every bill
- Insurer pays 80%
- Premium: KES 38,000/year
Savings: KES 17,000/year (31%)
The math:
If your annual medical bills = KES 50,000:
- You pay: KES 10,000 (20% co-payment)
- Premium savings: KES 17,000
- Net savings: KES 7,000
Worth it? Yes, if you're generally healthy.
Strategy 6: Buy During Enrollment Periods (Avoid Loading)
Some insurers offer open enrollment periods:
- No medical exams
- No age loading
- Faster approval
When:
- January-February (most insurers)
- June-July (some insurers)
Why it matters:
Outside enrollment = medical questionnaires, possible premium loading.
During enrollment = cleaner, cheaper.
Strategy 7: Bundle with Other Insurance (Get Discounts)
If you have a car or business:
Bundle:
- Health insurance
- Motor insurance
- Business insurance
Discount: 10-15% on total
Example:
Separate purchases:
- Health: KES 50,000
- Motor: KES 25,000
- Business: KES 15,000
- Total: KES 90,000
Bundled:
- All three from same insurer
- 15% discount
- Total: KES 76,500
Savings: KES 13,500
Best insurers for bundling:
- CIC
- Britam
- Jubilee
Best Health Insurers for Self-Employed
1. Britam (Best Overall)
Why: ✔ Competitive pricing ✔ Accepts small groups (min. 3) ✔ Good digital tools ✔ Fast approvals
Sample premium (35-year-old): KES 45,000/year
2. Madison (Best for Flexibility)
Why: ✔ Flexible underwriting ✔ Willing to negotiate ✔ Good for chronic conditions
Sample premium (35-year-old): KES 42,000/year
3. Resolution Health (Best Transparency)
Why: ✔ Clear pricing ✔ Transparent terms ✔ Great app
Sample premium (35-year-old): KES 48,000/year
4. Jubilee (Best for Families)
Why: ✔ Best maternity ✔ Large network ✔ Trusted brand
Sample premium (35-year-old): KES 52,000/year
Tax Deductions for Self-Employed
Good news: Health insurance premiums are tax-deductible.
How it works:
Example:
- Annual income: KES 1,200,000
- Health insurance: KES 60,000
- Tax rate: 30%
Tax savings: KES 18,000 (30% of KES 60,000)
Real cost of insurance: KES 42,000 (KES 60,000 - KES 18,000)
How to claim:
Include health insurance premiums in your annual tax return (iTax).
Supporting documents:
- Insurance receipts
- Policy document
What If You Have Irregular Income?
Freelancing = unpredictable income.
Options:
Option 1: Pay Annually (When You Have Cash)
One big payment when income is good.
No monthly stress.
Option 2: Monthly Payments (Spread Cost)
Easier on cash flow.
But costs 5-10% more.
Option 3: Emergency Fund + Inpatient-Only
Strategy:
- Buy basic inpatient cover (KES 20,000/year)
- Build emergency fund for outpatient (KES 50,000)
- Use emergency fund for doctor visits
Total: Same cost, more control.
Can You Deduct Premiums as Business Expense?
If you're a sole proprietor: Yes (for you and dependents)
If you're a limited company: Yes (if company pays for it)
How:
- Include in business expenses
- Attach receipts to tax returns
- Reduces taxable income
Consult accountant to maximize deductions.
What About Maternity (If You're Planning a Family)?
Maternity is expensive to add:
Individual maternity: +KES 15,000 - 25,000/year
Waiting period: 10-12 months
Strategy:
If planning kids in next 2 years:
- Add maternity NOW
- Wait out waiting period
- Get pregnant after waiting period ends
Don't wait until pregnant. Won't be covered.
Handling Renewals (Premium Increases)
Expect 10-15% annual increases.
How to manage:
Strategy 1: Shop Around at Renewal
Get 3-5 competing quotes.
Use them to negotiate with current insurer.
Strategy 2: Switch Insurers
If increase is >20%, switch.
Note: Pre-existing conditions restart waiting periods.
Strategy 3: Adjust Coverage
Drop outpatient. Keep inpatient.
Or increase co-payment.
Strategy 4: Lock in Multi-Year Rates
Some insurers offer 2-3 year rate locks (rare).
Ask about it.
Red Flags: Insurers to Avoid
Warning signs:
❌ Claims consistently rejected ❌ Payment delays beyond 30 days ❌ Poor IRA ratings ❌ Sudden premium hikes (>25%) ❌ Hidden fees
Stick to established insurers:
- AAR
- Jubilee
- Britam
- Madison
- Resolution
- CIC
Common Mistakes Self-Employed Make
Mistake 1: Waiting until sick to buy insurance
Solution: Buy when healthy. Pre-existing conditions = waiting periods.
Mistake 2: Buying cheapest without checking network
Solution: Confirm preferred hospitals are covered.
Mistake 3: Not claiming tax deductions
Solution: Always deduct premiums from taxable income.
Mistake 4: Letting policy lapse (then buying new)
Solution: Keep policy active. Lapsing = new medical exams, waiting periods.
Mistake 5: Not shopping around
Solution: Get 3-5 quotes annually.
Real Case Studies
Case 1: Sarah, 32, Freelance Graphic Designer
Challenge: KES 55,000/year individual premium too expensive
Solution:
- Joined IHRM as associate member (KES 15,000)
- Got group rate health insurance (KES 38,000)
- Total: KES 53,000 (saved KES 2,000 + better coverage)
Case 2: James, 41, Consultant
Challenge: KES 75,000/year for inpatient + outpatient
Solution:
- Switched to inpatient-only (KES 45,000)
- Uses SHA for outpatient (included in taxes)
- Savings: KES 30,000/year
Case 3: Mary, 28, Content Creator
Challenge: Irregular income, can't afford annual payment
Solution:
- Monthly payment plan (KES 4,200/month)
- Set up auto-debit to avoid lapses
- Total: KES 50,400/year (slightly more, but manageable)
Your Action Plan
This week:
- Get quotes from 3-5 insurers
- Research professional associations you can join
- Calculate tax deductions
This month:
- Choose best option (individual, group, or association)
- Apply and get covered
- Set up payment (annual or monthly)
Ongoing:
- Set renewal reminders (60 days before)
- Track medical expenses (for tax)
- Re-evaluate annually
Next Steps
- Calculate your budget (3-5% of annual income)
- Decide: inpatient-only or full package?
- Check if you qualify for group/association rates
- Get 3-5 quotes
- Compare:
- Premium
- Network
- Coverage limits
- Buy and start claiming tax deductions
Being self-employed doesn't mean overpaying for insurance.
You just need to:
- Join groups
- Use SHA + top-ups
- Negotiate co-payments
- Claim tax deductions
Do that, and you'll pay 30-50% less than the "standard" rate.
Start Generating Quotes in Minutes
Compare quotes from Kenya's leading insurers and send a client a proposal in under a minute.
No credit card required.
Get quotes from 40+ underwriters in under 30 seconds.
All quotes meet Insurance Regulatory Authority standards.
Never miss a commission payment with automatic tracking.